Theon International — Goggles, gimbals and growth

Theon International (AMS: THEON)

Last close As at 30/10/2026

EUR30.42

▲ −0.22 (−0.72%)

Market capitalisation

EUR2,392m

More on this equity

Research: Industrials

Theon International — Goggles, gimbals and growth

Theon’s H126 revenue grew by 35% to €248.7m, with adjusted EBIT up 37% to €65.1m, equating to an adjusted EBIT margin of 26.2%, up 40bp y-o-y. Order intake increased by 38.5% to €232.5m (H125: €167.9m), reflecting continued demand across Theon’s products and taking the soft backlog to €1.46bn, providing good forward revenue visibility. FY26 revenue guidance was upgraded by c 2.5%, with adjusted EBIT margins now guided to ≥26%, from the mid-20s previously, for both FY26 and the medium term. Growth is well underpinned by orders, robust end markets and strategic initiatives, with ISR continuing to scale. Our updated DCF/SOTP valuation of €42.1 per share (€35.3 previously) implies almost 40% upside.

Written by

Jonathan Day

Director of Content, Industrials

Aerospace and defence

Update note

2 November 2026

Price €30.64
Market cap €2,409m

Net cash/(debt) end Q226

€(237.9)m

Shares in issue

78.6m
Free float 29.0%
Code THEON
Primary exchange AEX
Secondary exchange N/A
Price Performance
% 1m 3m 12m
Abs 5.7 (6.9) 10.5
52-week high/low €39.5 €23.3

Business description

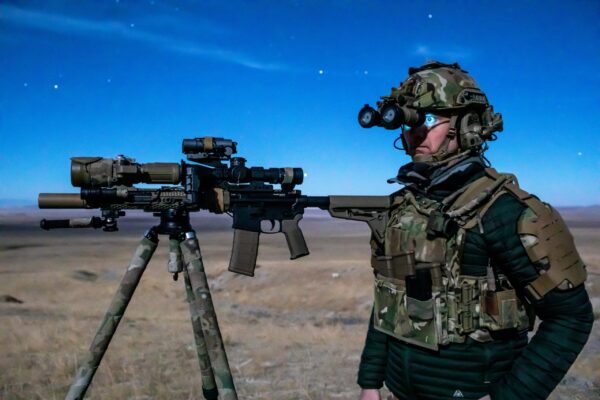
Theon International develops and manufactures customisable night vision and thermal imaging systems, primarily for military and security applications. These optoelectronic devices are developed for both man-portable and ISR applications.

Next events

Q3 trading update

9 November

Analysts

Jonathan Day
+44 (0)20 3077 5700
Harry Kilby
+44 (0)20 3077 5700

Theon International is a research client of Edison Investment Research Limited

Note: PBT and EPS are normalised, excluding exceptional items and share-based payments.

Year end Revenue (€m) PBT (€m) EPS (EUc) DPS (EUc) P/E (x) Yield (%)
12/24 352.4 86.7 98.00 34.00 31.3 1.1
12/25e 443.4 105.5 115.00 31.00 26.6 1.0
12/26e 607.0 155.8 152.00 37.00 20.2 1.2
12/27e 757.5 171.0 164.00 42.00 18.7 1.4

Strong H126 results, guidance upgraded

H126 revenue increased 35% to €248.7m (H125: €183.7m), with adjusted EBIT up 37% to €65.1m (H125: €47.4m), equating to an adjusted EBIT margin of 26.2%, up 40bp y-o-y. Cash conversion of c 83% remains at a good level. Strong orders reflect continued demand across Theon’s products, while the soft backlog of €1.46bn represents 2.4x forward-looking coverage, providing revenue visibility supported by exposure to multi-year procurement programmes, framework agreements and high customer retention. FY26 revenue guidance was upgraded by c 2.5% to c €600m. Theon raised adjusted EBIT margin guidance from the mid-20s to ≥26% for both FY26 and the medium term. Management regards the guidance as conservative.

ISR growth margin-positive, peer guidance supportive

Theon continues to expand its growth ecosystem and ISR business, with ISR seeing rising customer interest while management successfully integrates recent acquisitions to rapidly secure synergies. Theon expects non-night vision revenues to reach c 19% of total FY26 sales, and we believe the growth of higher-margin ISR revenues underpins the company’s mid-term margin guidance upgrade. In addition, on 17 September Theon’s peer Exosens (in which Theon holds a 9.8% stake) upgraded its FY26 guidance for revenue and EBITDA by 6% and 9%, respectively, driven by faster production and growing demand for image intensifier tubes that are used in Theon’s night vision goggles, with positive implications for Theon.

Updated valuation implies c 40% upside

Theon’s shares have fallen by c 25% (Exhibit 6) from an August 2026 peak of c €39.5. Its one-year forward P/E is now below its average since our data began in April 2024. We struggle to justify the de-rating given robust company and sector fundamentals and recent supportive newsflow. We believe Theon is well-placed to benefit from strong end market growth with sector-leading margins. Our updated 50/50 DCF/SOTP-based valuation of €42.1/share (€35.3 previously) implies almost 40% upside.

Company overview

Theon International is a leading developer and manufacturer of customisable night vision and thermal imaging systems for military and security applications in Europe, with a global footprint spanning 72 countries. The company designs and manufactures cutting-edge optoelectronic devices for both man-portable and ISR (Intelligence, Reconnaissance, Surveillance) systems, enabling the visualisation of images in low-light or obscured conditions using state-of-the-art technologies. Product design is handled by Theon’s experienced in-house engineering team. Theon has been actively diversifying its product mix. Its Intelligence, Surveillance and Reconnaissance (ISR) activities have been expanded through a series of acquisitions and partnerships that position Theon for growth across land, sea and air.The company is well positioned to capture growth in its end markets, with 2025–30 CAGRs for the night vision market of c 11% and for the ISR (formerly Platforms) market of c 12%. Theon’s order intake and revenue grew c 38% and 35% respectively in H126 and the company guides to sales growth of 15% in the medium term, with recently upgraded margin guidance suggesting margins of at least 26% in FY26 and the medium term compared to the mid-20s previously. A series of strategic initiatives, including acquisitions, supports a broader offering and ISR ecosystem development, while Theon’s 9.8% stake in Exosens underpins tube supply for night vision goggles. A strong growth and margin profile drives our suggested valuation of €42.1, which offers almost 40% upside given recent share price weakness despite robust fundamentals. Balance sheet deleveraging following recent strategic initiatives supports the company’s target to pay out 20–30% of net income in dividends.

For more about Theon see our July 2026 outlook note.

H126 results, guidance upgraded

Theon announced a trading update after the close on 27 July 2026, delivering a robust set of results for Q226, with revenues of €128.6m (€92.9m) up 38% and EBIT up 44% to €35.1m (€24.3m), equating to an adjusted EBIT margin of 27.3%, up 110bp y-o-y. Q2 saw continued strong demand for night vision solutions and the group continued to build traction across ISR solutions (formerly the Platforms business), with the announced HGH acquisition marking Theon’s entry into counter-drone systems.

Q226 and H126 numbers were confirmed with the full H126 results released on 7 September. H126 revenue was up 35% to €248.7m (H125: €183.7m), with adjusted EBIT up 37% to €65.1m (€47.4m), equating to an adjusted EBIT margin of 26.2%, up 40bp y-o-y. Cash conversion of c 83% was slightly lower than the 86% in H125 but remains at a good level. Net debt remained broadly stable in Q226 at €238m (Q1: €228m) with net debt/EBITDA of 1.7x before the recently announced acquisition of an 80% stake in Merio and the acquisition of HGH for c €300m, which the company expects to complete by late Q426/early Q127 and beginning of 2027, respectively.

Order book provides visibility

H126 order intake increased by 38.5% to €232.5m in H126 (H125: €167.9m), reflecting continued demand across Theon’s products and taking the soft backlog to €1.46bn. This represents 2.4x forward-looking coverage based on the top end of Theon’s guidance range and provides visibility of future growth supported by Theon’s exposure to multi-year procurement programmes, framework agreements and high customer retention.

Net debt expected to peak in FY27

H126 net debt of €237.9m equates to 1.7x last 12-months (LTM) EBITDA. Theon envisages leverage peaking at <2.5x EBITDA in FY27 before falling to <2.0x in FY28, and the company highlights that pro forma leverage after monetising liquid assets would be c 1.1x in FY26, <1.0x in FY27 and <0.5x in FY28. Theon is well funded and sees no imminent need to raise additional debt.

Revenue and margin guidance upgraded

Theon continues to benefit from resilient demand fundamentals, providing confidence in the achievement of FY26 guidance. On the H126 results call, three components of guidance were upgraded:

  1. FY26 revenue was upgraded to c €600m from €570–600m, up 2.5% based on the €585m mid-point.
  2. FY26 adjusted EBIT margins were upgraded to ≥26% from the mid-20s.
  3. Medium-term adjusted EBIT margin guidance was also upgraded to ≥26% from the mid-20s.

Guidance for organic sales growth of 15% per year in the medium term, FY26 capex of €30m, capex/sales of c 4% in the medium term and dividends at 20–30% of net income were unchanged.

While some decisions in the Middle East and APAC region have been delayed, the company sees this as a temporary shift, noting that delayed programmes should resume. Theon expects further acceleration of activity and order intake in the second half of 2026, in line with the sector’s typical seasonality and the company’s historical business pattern, supported by what Theon describes as a robust pipeline, new products and opportunities across geographies, which also expand the company’s addressable market. Theon notes that demand for soldier and man-portable equipment remains strong, especially in Europe, with this reflected in c €50m of order wins announced on 30 September.

Conservative approach to guidance

Management emphasised on the results call, and again in the c €50m September order announcement, that it prefers to take a conservative approach with regard to guidance so that it can deliver positive surprises.

Exosens September guidance upgrade supportive for Theon

In January 2026, Theon acquired a 9.8% stake in Exosens, a European leader in high-end electro-optical technologies for defence and industrial applications. One of its major product lines is image intensifier tubes (IITs), which are the key component for Theon’s night vision systems. The stake reinforces Theon’s medium-term supply agreement with Exosens for IITs and facilitates collaboration between the two companies in areas such as next-generation tubes. Theon confirmed on the H126 call that it views the stake as sufficient and a strategic investment, with the focus now on the partnership.

Exosens raised its FY26 guidance on 17 September, increasing expectations for revenue of €558–570m from €520–540m and adjusted EBITDA of €186–192m from €168–178m. At the mid-points of each range this equates to upgrades of c 6% and 9%, respectively, with Exosens guiding to year-on-year growth of c 20% in revenue and c 25% adjusted EBITDA at the mid-points. The upgrade was driven by faster-than-expected ramp-up of additional European production capacity for high-performance IITs to meet growing global demand and the accelerating adoption of mission-critical imaging technologies across drone, counter-drone and long-range surveillance applications. Exosens’ shares reacted positively, gaining 8.4% on the day, while Theon gained 2.8%.

We believe the Exosens guidance upgrade has positive implications for Theon given the growing demand driving IIT capacity, which should be beneficial to Theon’s core man-portable imaging activities, while the accelerated adoption of imaging in drones and surveillance supports both Theon’s strategy to build its ISR business and the associated growth prospects.

M&A and strategic initiatives: Expanding the growth ecosystem

In our previous note, we highlighted that Theon had been active in M&A, using targeted deals to add complementary products and broaden organic growth. Recent notable events include:

  • The c €300m agreed acquisition of HGH Systèmes Infrarouges, announced on 17 June 2026, which materially increases the contribution of ISR electro-optics and adds counter-unmanned aerial systems (CUAS) capability. HGH provides passive detectors for drones, meaning they cannot be detected by an enemy, and Theon expressed confidence in the system on the earnings call. Importantly, Theon points to margin accretion in year one of the HGH deal following expected completion in Q127. Theon views HGH as important for future guidance, as it would like to double the €40m revenue HGH is expected to generate in FY26. This additional volume, together with better fixed-cost absorption, is what makes it confident of achieving margin accretion.
  • A memorandum of understanding with Safran Electronics and Defense signed on 15 June 2026 to establish a joint venture (JV) for airborne electro-optical and infrared systems for UAVs, focused on small gimbals for ISR and targeting applications.
  • The May 2026 agreed acquisition of an 80% stake in the French company Merio, which accelerates Theon’s growth prospects in the air domain with a quicker entry into unmanned aerial systems. Merio designs and manufactures compact, high-performance gyrostabilised gimbal and turret systems for aerial, ground, infrastructure protection and emerging maritime applications with embedded AI-driven video-processing capabilities. Theon has identified opportunities from this transaction, which it expects to close in late Q426/early Q127, with comments on the H126 call highlighting that Merio strengthens Theon’s position in France and supports both the JV with Safran and Theon’s aim to be a leading global gimbals company by the end of 2027. Theon expects amplification of Merio’s capabilities to drive gains in market share.

ISR continues to scale

The M&A and strategic initiatives above have contributed to strong foundations for Theon’s ISR business, which is seeing rising interest in many of its products, including drones, as the company builds its ISR ecosystem.

Management’s focus is on integration and synergies, with the company stating that the speed of integration is unprecedented and has commenced in some cases while seeking final approvals in order to achieve swift and visible results.

We expect this approach to deliver, and we point to management’s track record of successful integration such as the threefold increase of production capacity at Harder Digital, the outperformance of Kappa compared to Theon’s targets and success with ShockEOS given the supply agreement with Rheinmetall.

Non-night vision supports ≥26% medium-term margin guidance

Theon is targeting 20% of revenue from ISR (formerly Platforms) in the medium term and highlighted in the H126 results that non-night vision revenue (ISR and non-night vision man-portable) was c 15% of total revenue and expected to reach c 19% by FY26. We believe this illustrates successful execution of Theon’s strategy to diversify through growth of ISR and non-night vision man-portable products such that in the medium term night vision revenue represents 50% of total revenue.

According to management, non-night vision products carry higher margins and this supports its confidence about margin evolution, with both FY26 and medium-term margin guidance upgraded to ≥26%.

Minor changes to forecasts

We make small changes to our forecasts (Exhibit 5) following the guidance upgrade, H126 results and M&A phasing, nudging up revenues by c 1% in FY26e, which feeds into FY27e. Theon’s improved adjusted operating margin guidance is reflected in our FY26 and FY27 forecasts, which increase by 10bp to 26.0% and 70bp to 26.4% respectively. Our higher net debt forecast for FY27, due to M&A phasing with HGH expected to complete in Q127, results in a higher interest charge and reduced EPS.

Performance and valuation

Despite the positive newsflow and improved guidance, Theon’s share price has faded recently, which may be due to markets waiting to see how orders develop at the end of the year and/or the prospect of temporarily slower EPS growth in 2027 due to higher interest charges before EPS growth resumes in 2028. However, FY27 revenue and adjusted EBIT growth remain robust (Exhibit 11). The one-year forward P/E of 16.7x has fallen below the average since data began in April 2024 following the 7 February 2024 IPO. Applying the P/E from around the middle of the year-to-date range of 21x to our FY27 normalised EPS of €1.64 would result in a share price of €34.4. Given Theon’s robust long-term growth prospects and fundamentals, along with a lack of negative newsflow, we believe the recent de-rating is hard to justify.

Given the robust growth outlook for Theon’s end markets and the company’s improved margin guidance, we believe the backdrop remains supportive. While there is some risk that geopolitical tensions ease, we would not expect this to result in significant changes to the outlook for defence markets, which is driven by re-arming against a more unstable geopolitical backdrop. Theon’s expansion of the ISR ecosystem should help mitigate the risk of changes in spending patterns away from man-portable equipment.

Our updated valuation using our 50/50 peer group/discounted cash flow methodology suggests a valuation of €42.1 per share and includes the value of the 9.8% stake in Exosens, which is worth c €3.6 per share.

We have updated our peer-based SOTP (Exhibit 8), which now includes a smaller specialist defence peer group as we have removed companies that were not representative of Theon’s electronics activities. We have then applied an 80% weighting to the enhanced vision systems peers and 20% to specialist defence peers (compared to 50/50 previously) to more accurately reflect Theon’s mix of activities. We have based our valuation on blended multiples rather than the averages of 2025/26/27 previously to better capture forward valuation measures. This results in a valuation of €29.8 per share (€30.8 previously).

Our updated DCF valuation (Exhibit 9) is now €44.4 per share (€39.8 previously) based on a 2% terminal growth rate and 7.2% weighted average cost of capital (WACC) with DCF sensitivity illustrated in Exhibit 10. The average of our DCF and SOTP approaches is €42.1 per share.


General disclaimer and copyright

This report has been commissioned by Theon International and prepared and issued by Edison, in consideration of a fee payable by Theon International. Edison Investment Research standard fees are £60,000 pa for the production and broad dissemination of a detailed note (Outlook) following by regular (typically quarterly) update notes. Fees are paid upfront in cash without recourse. Edison may seek additional fees for the provision of roadshows and related IR services for the client but does not get remunerated for any investment banking services. We never take payment in stock, options or warrants for any of our services.

Accuracy of content: All information used in the publication of this report has been compiled from publicly available sources that are believed to be reliable, however we do not guarantee the accuracy or completeness of this report and have not sought for this information to be independently verified. Opinions contained in this report represent those of the research department of Edison at the time of publication. Forward-looking information or statements in this report contain information that is based on assumptions, forecasts of future results, estimates of amounts not yet determinable, and therefore involve known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of their subject matter to be materially different from current expectations.

Exclusion of Liability: To the fullest extent allowed by law, Edison shall not be liable for any direct, indirect or consequential losses, loss of profits, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note.

No personalised advice: The information that we provide should not be construed in any manner whatsoever as, personalised advice. Also, the information provided by us should not be construed by any subscriber or prospective subscriber as Edison’s solicitation to effect, or attempt to effect, any transaction in a security. The securities described in the report may not be eligible for sale in all jurisdictions or to certain categories of investors.

Investment in securities mentioned: Edison has a restrictive policy relating to personal dealing and conflicts of interest. Edison Group does not conduct any investment business and, accordingly, does not itself hold any positions in the securities mentioned in this report. However, the respective directors, officers, employees and contractors of Edison may have a position in any or related securities mentioned in this report, subject to Edison's policies on personal dealing and conflicts of interest.

Copyright 2026 Edison Investment Research Limited (Edison).

Australia

Edison Investment Research Pty Ltd (Edison AU) is the Australian subsidiary of Edison. Edison AU is a Corporate Authorised Representative (1252501) of Crown Wealth Group Pty Ltd who holds an Australian Financial Services Licence (Number: 494274). This research is issued in Australia by Edison AU and any access to it, is intended only for "wholesale clients" within the meaning of the Corporations Act 2001 of Australia. Any advice given by Edison AU is general advice only and does not take into account your personal circumstances, needs or objectives. You should, before acting on this advice, consider the appropriateness of the advice, having regard to your objectives, financial situation and needs. If our advice relates to the acquisition, or possible acquisition, of a particular financial product you should read any relevant Product Disclosure Statement or like instrument.

New Zealand

The research in this document is intended for New Zealand resident professional financial advisers or brokers (for use in their roles as financial advisers or brokers) and habitual investors who are “wholesale clients” for the purpose of the Financial Advisers Act 2008 (FAA) (as described in sections 5(c) (1)(a), (b) and (c) of the FAA). This is not a solicitation or inducement to buy, sell, subscribe, or underwrite any securities mentioned or in the topic of this document. For the purpose of the FAA, the content of this report is of a general nature, is intended as a source of general information only and is not intended to constitute a recommendation or opinion in relation to acquiring or disposing (including refraining from acquiring or disposing) of securities. The distribution of this document is not a “personalised service” and, to the extent that it contains any financial advice, is intended only as a “class service” provided by Edison within the meaning of the FAA (i.e. without taking into account the particular financial situation or goals of any person). As such, it should not be relied upon in making an investment decision.

United Kingdom

This document is prepared and provided by Edison for information purposes only and should not be construed as an offer or sol icitation for investment in any securities mentioned or in the topic of this document. A marketing communication under FCA Rules, this document has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.

This Communication is being distributed in the United Kingdom and is directed only at (i) persons having professional experience in matters relating to investments, i.e. investment professionals within the meaning of Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, as amended (the "FPO") (ii) high net-worth companies, unincorporated associations or other bodies within the meaning of Article 49 of the FPO and (iii) persons to whom it is otherwise lawful to distribute it. The investment or investment activity to which this document relates is available only to such persons. It is not intended that this document be distributed or passed on, directly or indirectly, to any other class of persons and in any event and under no circumstances should persons of any other description rely on or act upon the contents of this document.

This Communication is being supplied to you solely for your information and may not be reproduced by, further distributed to or published in whole or in part by, any other person.

United States

Edison relies upon the "publishers' exclusion" from the definition of investment adviser under Section 202(a)(11) of the Investment Advisers Act of 1940 and corresponding state securities laws. This report is a bona fide publication of general and regular circulation offering impersonal investment-related advice, not tailored to a specific investment portfolio or the needs of current and/or prospective subscribers. As such, Edison does not offer or provide personal advice and the research provided is for informational purposes only. No mention of a particular security in this report constitutes a recommendation to buy, sell or hold that or any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.

London │ New York │ Frankfurt

20 Red Lion Street

London, WC1R 4PS

United Kingdom

More on Theon International

View All

Latest from the Industrials sector

View All Industrials content

Research: Healthcare

Percheron Therapeutics — HMBD-002 moves closer to clinic with FDA greenlight

Percheron Therapeutics has taken a key step towards the clinic for lead asset HMBD-002, with FDA regulatory clearance for Vanderbilt Health-led investigator-sponsored trial in acute myeloid leukaemia (AML) and myelodysplastic syndrome (MDS). The study will evaluate HMBD-002 alongside standards of care azacitidine and venetoclax in up to 20 patients with relapsed/refractory (r/r) AML or AML/MDS, with dose optimisation the immediate focus. With trial drug product already in place, we believe the current announcement removes another execution hurdle. While we note that the cohort size is smaller than the 29–38 patients previously anticipated, we continue to view the investigator-sponsored approach as a credible, capital-efficient route to generating preliminary clinical evidence, albeit with reduced control over recruitment and timelines. Management expects recruitment to initiate in H1 CY27, and we believe that establishing preliminary efficacy and securing funding for broader development will be the key de-risking milestones.

Continue Reading
Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.