bp plc is a client of Edison Group. Edison Group produces and distributes this and other content. Edison does not hold any position in bp plc.
In our first two reports, we looked at bpx energy, bp’s US onshore business: how quickly it is growing, and how it is producing more with fewer rigs, lower unit costs and less capital. For investors weighing an investment in bp, the final step is to put that in the context of the whole company.
That means looking at bp group figures, which cover all of bp’s upstream, downstream and trading businesses around the world.
The first priority: The balance sheet
CEO Meg O’Neill has put strengthening the balance sheet at the top of her five priorities for bp. Her reasoning is direct: ‘Too much cash is currently being used to service liabilities. I want more of the value proposition to move back to equity holders – through growth, distributions, or both.’ She has also said that ‘a stronger balance sheet gives us more resilience, more flexibility, and greater capacity to create value through the cycle.’
The third quarter of 2026 showed progress.
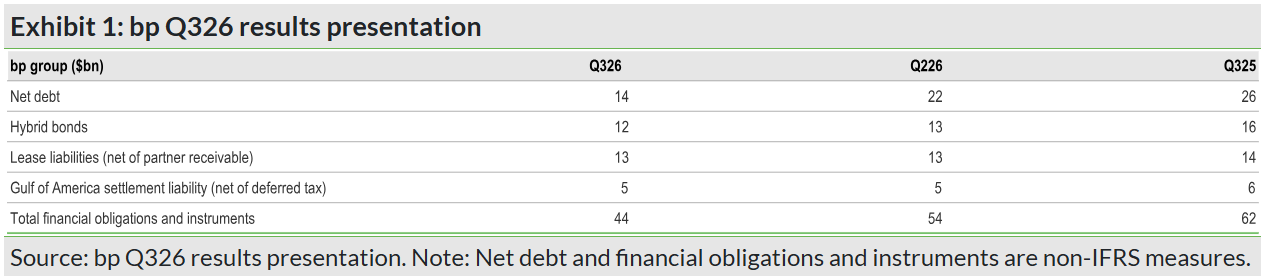
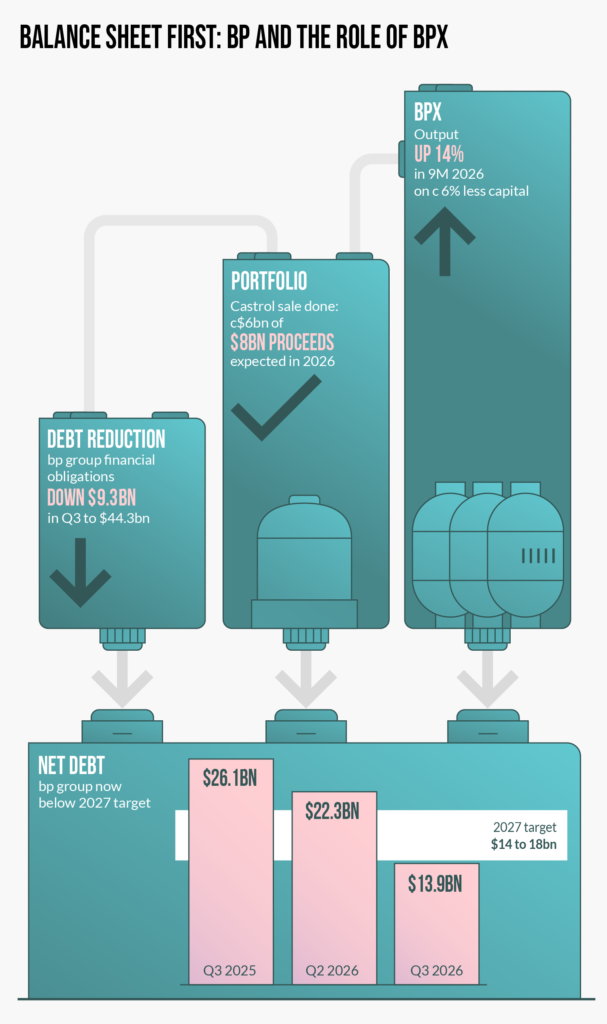
bp’s total financial obligations fell by around $9.3bn in the quarter, helped by stronger earnings, operating cash flow of $14.8bn and the redemption of $1.0bn of hybrid securities. Net debt fell by around $8.4bn to $13.9bn, already below the $14–18bn range bp had targeted for the end of 2027.
Looking ahead, bp expects financial obligations to fall to around $33–35bn by the end of 2026, Q4 assumptions that include Brent crude at $110 a barrel and around $8bn of divestment proceeds. Most of those divestments have already arrived: bp completed the sale of a 65% stake in Castrol in early November, bringing in around $6bn of proceeds. A further $1.06bn was raised by a selling a 5% stake in Norwegian producer Aker, which was announced on 5 November 2026. Management has been clear that this is not the end point. O’Neill said bp is ‘still too leveraged’ and that strengthening the balance sheet ‘remains our number one job’. bp also now intends to prioritize excess cash flow to address its remaining Deepwater Horizon liabilities in full.
Exhibit 2 – Balance sheet first: bp and the role of bpx
Source: Edison Investment Research
High-grading the portfolio
The second priority is simplifying the portfolio. bp is reviewing its businesses ‘asset by asset, business by business’, looking at cash generation, returns, capital efficiency and strategic fit. As O’Neill put it: ‘Some assets may have been important to bp in the past. That does not necessarily mean they are the right assets for bp’s future.’
This is already producing decisions at group level. In the third quarter, bp completed the sale of its Gelsenkirchen refinery in Germany and agreed to sell its Austrian retail business. It also brought in partners to share the risk and future capital of three upstream opportunities. It agreed terms to bring partners into its Kirkuk development in Iraq, and agreed for Shell to take a 50% stake in the Tupinambá exploration block offshore Brazil and a 30% stake in the Conifer prospect in the deepwater Gulf of America, with bp remaining operator of both. It has also launched processes to market its North Sea business and Archaea Energy, and in early November it completed the Castrol sale and sold down its stake in Aker. bp expects around $9bn of divestment and other proceeds in 2026, around $1bn more than it guided at its third-quarter results. bp also recorded $4.0bn of post-tax impairments in the third quarter, largely in transition businesses such as Lightsource bp and offshore wind. O’Neill was direct: ‘We know we need to be better stewards of our shareholders’ capital.’
bp has also delivered $4bn of structural cost reductions since 2023, bringing it within its $4–5bn target range. Chief financial officer Kate Thomson has acknowledged that much of that saving has been absorbed by inflation, acquisitions and activity choices, and that more needs to show through in the bottom line.
Where bpx fits
Portfolio high-grading is not only about selling assets. The same tests of cash generation, returns and capital efficiency determine which businesses bp chooses to grow.
On those tests, bpx is well placed. O’Neill has said it has ‘the ability to generate competitive returns, competitive cash flow’ and described it as ‘very much an integral part of the group’. On the third-quarter call, she said the opportunity is to ‘take what we’ve done in bpx and embed it everywhere else’. Its operating record supports that view: over the first nine months of 2026, bpx grew production by around 14% while running fewer rigs, lowering its production costs per barrel and spending around 6% less capital than a year earlier.
- Growth visibility. bp plans for bpx production to reach 650,000boepd in 2030, from 529,000boepd in Q326.
- Resource depth. bp estimates that bpx has more than 7bn barrels of oil equivalent of resources, which supports long-term growth and gives it the flexibility to direct activity toward oil or gas as prices change. Of that, 1,835m barrels of oil equivalent were classified as net proved reserves at the end of 2025.
- Flexibility. As a short-cycle business, bpx’s activity can be adjusted relatively quickly, complementing bp’s long-life deepwater and international assets. In Q3, bpx moved a rig from the Haynesville to the Eagle Ford.
bp’s third-quarter profit reflected many factors, above all sharply higher refining margins and a strong trading result. bpx’s role is different: it gives bp an efficient US business in which capital can be put to work and start producing quickly, and which has to keep competing for that capital with bp’s other opportunities.
The income picture
For income-focused investors, the dividend remains central. bp held its third-quarter dividend at 8.660c per ordinary share, following a 4% increase at the second quarter. US holders are expected to receive $0.5196 per American depositary share before fees, payable on 18 December. The share buyback was suspended in February 2026 so that excess cash could go to strengthening the balance sheet.
bp has now set out how it thinks about capital allocation, built on three priorities. The first is a ‘committed dividend’, which bp describes as the first call on its cash flow and one that shareholders need confidence it will deliver through the cycle. The second is disciplined investment through the cycle to improve asset performance and maximize cash flow, with growth capital going where bp sees ‘accretive and distinctive returns’. The third is sharing upside with shareholders, with share buybacks a tool bp can use ‘as and when appropriate’. O’Neill has said that the most important measure of whether bp is becoming more valuable is total shareholder return, delivered ‘through share price appreciation and dividends cash distributions’. bp will set out its full financial frame at its strategy and outlook update in New York on 15 December. Future dividends and any other shareholder distributions remain subject to the discretion of bp’s board.
What to watch
- Commodity prices. bp’s balance sheet expectations for 2026 rest on stated price assumptions. Lower prices would slow the pace of deleveraging. Weaker US gas prices also affect bpx’s realized prices and where it deploys rigs.
- Divestment timing and value. bp has said it will not sell assets at any price, so the timing of proceeds may vary.
- Cost and operational delivery. bp has acknowledged that safety performance and the pace of cost reduction are not yet where they need to be.
- Sustaining bpx’s efficiency. The gains described in our previous report need to be repeated over several quarters to be convincing.
- bp’s strategy day, 15 December. bp’s strategy and outlook update will set out its longer-term plans, capital frame and targets, including how it intends to share upside with shareholders.
Some investors remain sceptical after bp’s previous changes of direction, and that caution is understandable. The answer bp is offering is measurable delivery, reported every quarter.
Why this matters for California investors
For California investors who value income and dislike unnecessary risk, bp’s current direction has a clear logic: repair the balance sheet first, concentrate the portfolio on assets that earn their place, and invest with discipline in the best growth opportunities.
bpx sits naturally within that plan. It is an efficient, growing US business that gives bp a place to invest where results show up quickly and can be tracked quarter by quarter. It is not the whole bp story, but it is a clear example of the kind of business bp wants more of: one that supports bp’s broader growth and value proposition as the company works to become ‘simpler, stronger and more valuable’.
Forward-looking statements, including bp’s plans, priorities and production expectations, are based on current expectations and planning assumptions. Actual results may differ materially based on various factors including, but not limited to, commodity prices, operational performance, regulatory changes and global economic conditions.
Shareholder distributions, including dividends and share buybacks, are subject to the discretion of the board and may vary based on factors including, but not limited to, commodity prices, cash flow generation, balance sheet considerations and general business conditions. Past distributions are not indicative of future distributions.