Aclara Resources — Integrated rare-earth platform takes shape

Aclara Resources (ARA)

Last close As at 28/10/2026

CAD2.67

▲ −0.05 (−1.84%)

Market capitalisation

CAD663m

More on this equity

Research: Metals & Mining

Aclara Resources — Integrated rare-earth platform takes shape

Aclara held an Investor Day on 20 October, outlining its strategy to build an integrated rare-earth supply chain spanning upstream production in Brazil and Chile, separation in the US and downstream metals and alloys. The event followed an updated preliminary economic assessment (PEA) for Penco and completion of basic engineering for Project Dynamo, bringing together project economics, funding strategy and a 2028–29 development timetable. While heavy rare earth elements (HREEs) remain an important differentiator, Aclara’s prospective production is diversified across NdPr, Dy/Tb, Y, Gd and Sm. Financing, permitting and offtake are now the key next steps.

Written by

Andrey Litvin

Energy and Resources Analyst

Metals and mining

QuickView

29 October 2026

Price C$2.67
Market cap C$662m
Price Performance
Share details
Code ARA
Listing TSX

Shares in issue

248.0m

Net cash/(debt)

C$60.5m

Business description

Aclara Resources is a rare-earth development company advancing ionic-clay projects in Brazil and Chile alongside planned separation and metals and alloys facilities in the US.

Bull points

  • Complementary ionic-clay projects provide diversified exposure across NdPr, Dy/Tb, Y, Gd and Sm.
  • Integrated upstream, separation and metallisation strategy provides a potential direct route to Western end customers.
  • Strategic shareholders and growing US government support provide multiple potential funding channels.

Bear points

  • c US$1.7bn of initial development capital remains to be funded.
  • Carina environmental licensing and substantial project financing remain outstanding.
  • Project economics and commercial terms remain sensitive to rare-earth pricing, product qualification and binding offtake.

Analyst

Andrey Litvin
+44 (0)20 3077 5700

EDISON QUICKVIEWS ARE NORMALLY ONE-OFF PUBLICATIONS WITH NO COMMITMENT TO WRITING ANY FOLLOW UP. QUICKVIEW NOTES USE CONSENSUS EARNINGS ESTIMATES.

Investor Day defines the integrated platform

Aclara is emerging as an integrated rare-earth platform with US-centred downstream operations, combining the upstream Carina and Penco projects with Project Dynamo separation and subsequent metals and alloys production. Carina provides most of the upstream scale, while Penco contributes a higher-value product mix. Together, the projects target average annual production of c 1.3kt NdPr, 233t Dy/Tb and 1.6kt Y, alongside Gd and Sm. The latest studies estimate post-tax NPV8 of US$1.66bn for Carina, US$344m for Penco and US$773m for Dynamo.

Funding and offtake move to the forefront

Penco and the Louisiana facilities target start-up in late 2028, followed by Carina in Q229. Potential funding sources include a non-binding US EXIM Letter of Interest for up to US$750m, DFC support for Carina and further investment from CAP, while management identified financing as the principal potential bottleneck. Three customer MoUs are signed, and another three are progressing, with product qualification and price-floor discussions aimed at converting this interest into bankable offtake. We see committed financing and binding commercial agreements as the key next de-risking events.

Valuation: Strategic value beyond the resource

At an enterprise value of c US$0.5bn, Aclara trades at a substantial discount to the headline value of its development portfolio, reflecting the funding requirement and execution. Recent industry M&A suggests that strategic value is increasingly being attached to integrated ex-China supply chains rather than resources alone, with transactions such as USA Rare Earth/Serra Verde and Energy Fuels/ASM combining upstream supply with processing and downstream capabilities. Aclara is pursuing a similar model, while delivery against its 2027 funding, offtake and construction milestones should be the key drivers of value realisation.

Source: LSEG Data & Analytics

Consensus estimates

Year end Revenue ($m) EBITDA ($m) PBT ($m) EPS ($) EV/EBITDA (x)
12/25 0.0 (8.6) (6.4) (0.04) N/A
12/26e 0.0 (9.1) (10.9) (0.04) N/A
12/27e 0.0 (9.4) (15.9) (0.05) N/A

From mine to metals: Integrated development model

The central message from Aclara's Investor Day was the company’s evolution from an upstream developer into an integrated rare-earth platform spanning mineral extraction, separation and metals and alloys. Carina in Brazil and Penco in Chile are designed to produce Super Pure Rare Earth Carbonate (SPREC), Aclara's proprietary c 99%-purity mixed rare-earth carbonate, for Project Dynamo in Louisiana, where Aclara plans to separate six principal rare-earth products before selectively converting NdPr, Dy and Tb into metals and alloys. The resulting model combines two sources of ionic-clay feedstock with proprietary upstream processing, conventional solvent-extraction separation and a route towards products suitable for permanent-magnet manufacturers.

The Investor Day also provided a more coherent development timetable across the portfolio. Penco and the Louisiana facilities are targeting first production in late 2028, followed by Carina in Q229. Technical work is at different stages across the value chain: Carina has completed a feasibility study, Penco has an updated PEA, Dynamo has completed basic engineering and the Metals & Alloys project has completed front-end loading stage 2 (FEL 2) engineering. All four projects now have well-defined capital requirements and established project economic profiles. Management characterised the technical phase as largely complete, with the transition to construction now primarily dependent on financing and offtake.

Updated Penco PEA adds definition to the upstream base

Published immediately ahead of the Investor Day, the updated Penco PEA provides the latest technical underpinning for the integrated strategy. The study is based on 35.8Mt of measured and indicated (M&I) mineral resources grading 2,095ppm total rare earth oxides (TREO), plus 2.2Mt of inferred resources. Approximately 74% of the M&I resource is in the measured category, while the mine plan assumes processing 30.8Mt over a 17-year life at an average rate of c 1.9Mtpa.

Average annual production is estimated at 732t of rare earth oxides (REO) contained in SPREC, including 128t NdPr, 44t Dy, 6t Tb and 400t Y, alongside Gd, Sm and smaller-volume HREEs. The study estimates a post-tax NPV8 of US$344m, a 26.1% internal rate of return (IRR) and a 3.2-year payback on total initial construction capex of US$244m. Average net revenue is US$155m per annum and EBITDA c US$101m pa on the study's long-term price assumptions. The high basket value is driven primarily by Penco's Y-rich product mix: Y represents c 55% of average REO production and is priced at US$250/kg in the study, below current ex-China pricing but materially above prevailing China prices.

The updated study also incorporates more up-to-date cost assumptions than the 2021 PEA. Initial capex has increased by US$115m, while operating costs have risen to US$28.9/t of clay processed from US$13.6/t. Aclara attributes the increases to flowsheet enhancements following three pilot campaigns, more developed mining and environmental plans, updated equipment quotations and general cost escalation. The mine life has nevertheless increased to 17 years as the processing inventory expands to 30.8Mt from 19.9Mt.

An important feature of the Penco economics is that the upstream model already incorporates downstream treatment. Average separation, commercial discounts and transport charges of US$72m pa, equivalent to c 32% of gross revenue, are included in the PEA. Aclara intends to process Penco SPREC at Dynamo on arm's-length terms, with the separation value therefore captured separately at the Louisiana facility. This provides a clear distinction between upstream economics and the incremental value attributed to separation.

Diversified product mix broadens market exposure

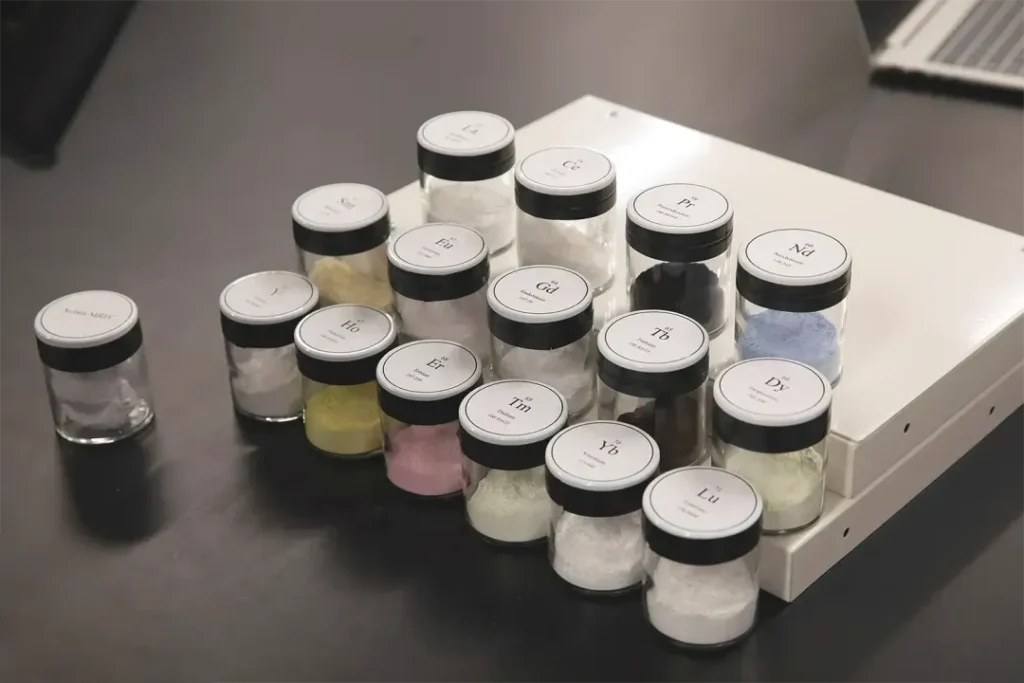
While Dy and Tb provide an important strategic differentiator, Aclara's planned product mix also includes meaningful NdPr, Y, Gd and Sm volumes. On a 100% project basis, Penco and Carina together target average annual production of c 1.3kt NdPr, 233t Dy/Tb, 1.6kt Y, 207t Gd and 192t Sm. Carina provides most of the absolute production scale, while Penco has the higher-value basket, reflecting a greater concentration of Y, Dy and Tb.

This broader exposure is relevant to the integrated model. NdPr gives Aclara access to the much larger permanent-magnet market, while Dy and Tb are scarce high-value additives required for certain high-temperature magnet applications. Y, Gd and Sm further diversify the product offering and potential customer base. Importantly, Project Dynamo is designed to separate NdPr, Dy, Tb, Y, Gd and Sm into individually saleable oxides in the US. Combining meaningful production of these elements with ex-China separation capacity would address one of the most constrained parts of the rare-earth supply chain.

Downstream development provides the route to market

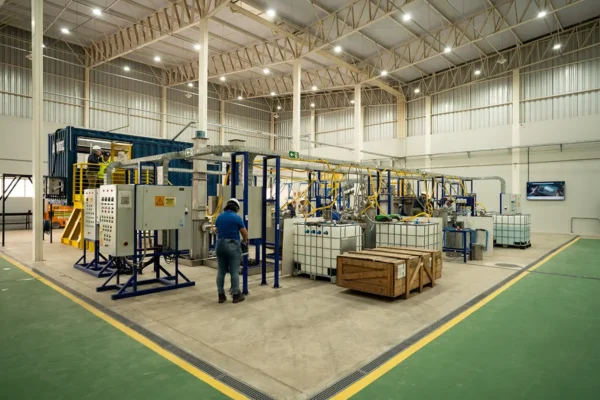
Project Dynamo is designed to convert SPREC into separated oxides using conventional solvent extraction in mixer-settlers. Basic engineering was completed in October, with the latest study estimating US$494m initial capex, a US$773m post-tax NPV8 and a 27.9% IRR. The use of commercially established solvent-extraction equipment should reduce scale-up risk relative to less proven separation technologies, although Aclara's specific flowsheet still needs to be demonstrated at commercial scale.

Product qualification is now becoming an increasingly important part of the commercial process. NdPr has already been produced at the targeted ≥99.5% purity at the Virginia Tech demonstration plant, while management now expects Dy and Tb samples in December, later than its initial August target as the separation circuits are progressively optimised. Prospective customers are requesting different products depending on their position in the value chain, ranging from SPREC to separated oxides and metals. Management indicated that successful sample qualification is an important step towards converting existing customer memoranda of understanding (MoUs) into binding offtake agreements.

The final downstream step is the proposed Metals & Alloys plant, owned 50/50 with CAP, a Chilean mining and industrial group with iron-ore, steel and infrastructure operations, and planned alongside Dynamo in Louisiana. The US$149m project targets NdPr metal, FeDy, Tb and c 2.7ktpa of NdFeB alloy. A demonstration plant inaugurated in Chile in October has a nominal NdPr-metal capacity of up to 175kg/day and had produced c 500kg by the time of the Investor Day event. Although this business accounts for a smaller proportion of the group's projected economics, it extends Aclara's addressable market towards magnet manufacturers and enables the company to offer customers products at several stages of the rare-earth value chain.

Permitting, funding and offtake become the main execution milestones

At Carina, the preliminary environmental licence (LP), the first stage of Brazil’s three-step environmental licensing process, remains the principal permitting milestone ahead of construction. Management expects the public hearing to be the next step and continues to target the LP by end-Q1 2027. Building all four projects requires c US$1.67bn of initial capital. Aclara is pursuing a staged funding strategy, with US government agencies progressing technical and ESG due diligence. The Export-Import Bank of the United States (EXIM) has issued a non-binding Letter of Interest for up to US$750m, while the US International Development Finance Corporation (DFC) has made an initial US$5m investment in Carina. CAP can invest a further US$50m to increase its Penco ownership from 20% to 40%, while management noted it is already structuring project finance for Penco with private banks and multilaterals. Management described financing as the principal potential bottleneck to the development timetable.

Offtake negotiations are being advanced in parallel with financing. Aclara has signed three private customer MoUs and noted that another three are in the pipeline, including one that is already closer to an offtake arrangement. Management also indicated that aggregate customer interest exceeds planned production and estimates that contracting roughly 50% of output for the first five to seven years could be sufficient to support repayment of construction financing, depending on achieved prices. Current negotiations are focused particularly on price floors and caps referenced to Western pricing benchmarks: securing a minimum bankable cash flow during the initial repayment period is taking precedence over retaining full upside exposure.

The two workstreams are interdependent. Potential lenders want greater visibility on offtake, while customers require product samples and confidence that the projects will be financed and built. Aclara is therefore using government-backed financing, customer MoUs and progressive product qualification to advance both processes in parallel. In our view, successful conversion of these discussions into committed financing and binding commercial contracts is now the most important near-term de-risking event.

US support underpins the integrated strategy

Aclara's current development and funding strategy is focused on the US. Project Dynamo and the Metals & Alloys facility are planned for Louisiana, while US government support extends across the value chain through EXIM, DFC and the Department of Energy, alongside technology collaboration with Argonne National Laboratory and state-level support in Louisiana. Management said US government funding provides a route to advance development while binding offtake agreements are still being negotiated, potentially accelerating construction relative to relying solely on conventional private financing. Brazil's new critical-minerals framework also places greater emphasis on domestic value addition; management noted that this could support future separation capacity in Brazil, although the practical implications remain unclear and do not affect the current Carina development plan.

Aclara's strategy is consistent with the direction of recent rare-earth industry M&A. USA Rare Earth's acquisition of Serra Verde combined operating Brazilian upstream supply with US separation and magnet ambitions, while Energy Fuels' acquisition of Australian Strategic Materials (ASM) added established metals and alloys capability to its upstream and separation portfolio. These transactions are not directly comparable to Aclara, but they illustrate growing strategic interest in platforms that connect ex-China resources with processing and downstream product capabilities.

Aclara is pursuing a similar model organically, with two complementary sources of mine feed, planned US separation and a route into metals and alloys. Following the Investor Day and updated Penco study, the architecture of that platform is becoming increasingly well-defined. The next step is execution: completing the remaining technical work, securing financing and offtake, and moving the first projects into construction during 2027.

General disclaimer and copyright

This report has been prepared and issued by Edison. Edison Investment Research standard fees are £60,000 pa for the production and broad dissemination of a detailed note (Outlook) following by regular (typically quarterly) update notes. Fees are paid upfront in cash without recourse. Edison may seek additional fees for the provision of roadshows and related IR services for the client but does not get remunerated for any investment banking services. We never take payment in stock, options or warrants for any of our services.

Accuracy of content: All information used in the publication of this report has been compiled from publicly available sources that are believed to be reliable, however we do not guarantee the accuracy or completeness of this report and have not sought for this information to be independently verified. Opinions contained in this report represent those of the research department of Edison at the time of publication. Forward-looking information or statements in this report contain information that is based on assumptions, forecasts of future results, estimates of amounts not yet determinable, and therefore involve known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of their subject matter to be materially different from current expectations.

Exclusion of Liability: To the fullest extent allowed by law, Edison shall not be liable for any direct, indirect or consequential losses, loss of profits, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note.

No personalised advice: The information that we provide should not be construed in any manner whatsoever as, personalised advice. Also, the information provided by us should not be construed by any subscriber or prospective subscriber as Edison’s solicitation to effect, or attempt to effect, any transaction in a security. The securities described in the report may not be eligible for sale in all jurisdictions or to certain categories of investors.

Investment in securities mentioned: Edison has a restrictive policy relating to personal dealing and conflicts of interest. Edison Group does not conduct any investment business and, accordingly, does not itself hold any positions in the securities mentioned in this report. However, the respective directors, officers, employees and contractors of Edison may have a position in any or related securities mentioned in this report, subject to Edison's policies on personal dealing and conflicts of interest.

Copyright 2026 Edison Investment Research Limited (Edison).

Australia

Edison Investment Research Pty Ltd (Edison AU) is the Australian subsidiary of Edison. Edison AU is a Corporate Authorised Representative (1252501) of Crown Wealth Group Pty Ltd who holds an Australian Financial Services Licence (Number: 494274). This research is issued in Australia by Edison AU and any access to it, is intended only for "wholesale clients" within the meaning of the Corporations Act 2001 of Australia. Any advice given by Edison AU is general advice only and does not take into account your personal circumstances, needs or objectives. You should, before acting on this advice, consider the appropriateness of the advice, having regard to your objectives, financial situation and needs. If our advice relates to the acquisition, or possible acquisition, of a particular financial product you should read any relevant Product Disclosure Statement or like instrument.

New Zealand

The research in this document is intended for New Zealand resident professional financial advisers or brokers (for use in their roles as financial advisers or brokers) and habitual investors who are “wholesale clients” for the purpose of the Financial Advisers Act 2008 (FAA) (as described in sections 5(c) (1)(a), (b) and (c) of the FAA). This is not a solicitation or inducement to buy, sell, subscribe, or underwrite any securities mentioned or in the topic of this document. For the purpose of the FAA, the content of this report is of a general nature, is intended as a source of general information only and is not intended to constitute a recommendation or opinion in relation to acquiring or disposing (including refraining from acquiring or disposing) of securities. The distribution of this document is not a “personalised service” and, to the extent that it contains any financial advice, is intended only as a “class service” provided by Edison within the meaning of the FAA (i.e. without taking into account the particular financial situation or goals of any person). As such, it should not be relied upon in making an investment decision.

United Kingdom

This document is prepared and provided by Edison for information purposes only and should not be construed as an offer or sol icitation for investment in any securities mentioned or in the topic of this document. A marketing communication under FCA Rules, this document has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.

This Communication is being distributed in the United Kingdom and is directed only at (i) persons having professional experience in matters relating to investments, i.e. investment professionals within the meaning of Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, as amended (the "FPO") (ii) high net-worth companies, unincorporated associations or other bodies within the meaning of Article 49 of the FPO and (iii) persons to whom it is otherwise lawful to distribute it. The investment or investment activity to which this document relates is available only to such persons. It is not intended that this document be distributed or passed on, directly or indirectly, to any other class of persons and in any event and under no circumstances should persons of any other description rely on or act upon the contents of this document.

This Communication is being supplied to you solely for your information and may not be reproduced by, further distributed to or published in whole or in part by, any other person.

United States

Edison relies upon the "publishers' exclusion" from the definition of investment adviser under Section 202(a)(11) of the Investment Advisers Act of 1940 and corresponding state securities laws. This report is a bona fide publication of general and regular circulation offering impersonal investment-related advice, not tailored to a specific investment portfolio or the needs of current and/or prospective subscribers. As such, Edison does not offer or provide personal advice and the research provided is for informational purposes only. No mention of a particular security in this report constitutes a recommendation to buy, sell or hold that or any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.

London │ New York │ Frankfurt

20 Red Lion Street

London, WC1R 4PS

United Kingdom

More on Aclara Resources

View All

Latest from the Metals & Mining sector

View All Metals & Mining content

Research: Investment Companies

Georgia Capital — Strong Q326 NAV and healthcare expansion

Georgia Capital (GCAP) delivered another strong quarter, with NAV per share increasing by 13.6% q-o-q in Georgian lari (GEL) terms to a record GEL198.91 at end-September 2026 (up 15.1% q-o-q in sterling to £57.69). This brings the first nine months of 2026 (9M26) increase to 28.6% in GEL and 35.9% in sterling. The largest contributor remained LSE-listed Lion Finance Group (LFG), whose share price increased by 26.8% q-o-q, adding 11.3pp to GCAP’s NAV per share growth. Operating performance across the three large private holdings contributed another 2.4pp, while NAV-accretive buybacks added 0.6pp. An important new development is GCAP’s plan to invest c GEL53m in expanding its healthcare services business over the next two to three years, focusing on private-pay specialist healthcare, outpatient services and diagnostic imaging. GCAP will contribute GEL10m, with the balance financed at the portfolio company level. Management targets a return on incremental invested capital of more than 20% once the investments are fully operational. It will also consider an IPO of the healthcare services business in the next three to five years.

Continue Reading
Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.