Abcourt Mines — Production ramp-up latest

Abcourt Mines (TSX: ABI)

Last close As at 05/10/2026

—

— 0.00 (0.00%)

Market capitalisation

—

More on this equity

Research: Metals & Mining

Abcourt Mines — Production ramp-up latest

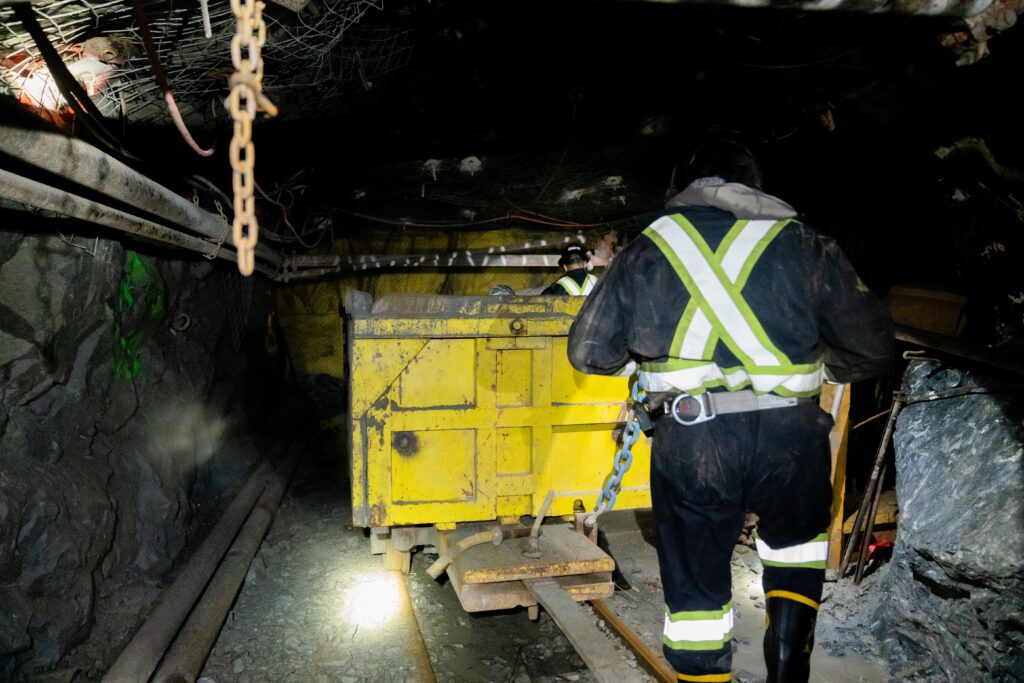
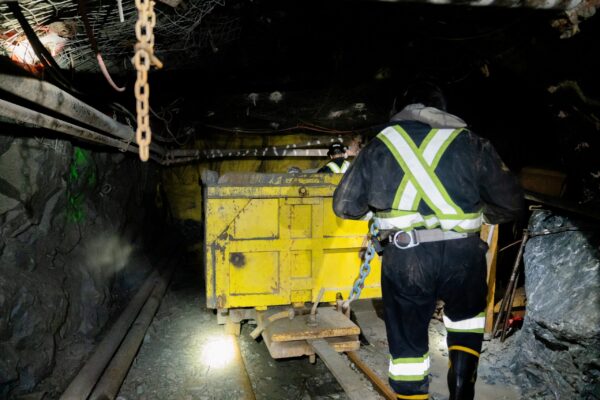
Abcourt Mines is ramping up its Sleeping Giant mine in the Abitibi region of Quebec. Until the summer, the ramp up had been focused on room-and-pillar stopes. However, Abcourt commissioned its first long-hole stope in April, after which the pace of ramp up has begun to accelerate towards its target throughput rate of 127.7ktpa (in line with the June 2023 PEA) and target production rate of c 30koz gold per year.

Written by

Lord Ashbourne

Director of Content, Mining

Metals and mining

August production update

6 October 2026

Price C$0.07
Market cap C$87m

C$1.4172/US$

Net cash/(debt) as at end-March

C$(21.2)m

Shares in issue

1,249.5m
Free float 69.0%
Code ABI
Primary exchange TSXV
Secondary exchange OTCQB
Price Performance
% 1m 3m 12m
Abs (17.6) 7.7 (33.3)
52-week high/low C$0.1 C$0.1

Business description

Abcourt Mines is an emerging gold producer and Canadian exploration company with strategically located mining properties in the prolific Abitibi region of Quebec in Canada.

Next events

FY26 results

October 2026

Q127 results

November 2026

Sleeping Giant gravimetric survey

CY26

Sleeping Giant scoping study

Early CY27

Analyst

Lord Ashbourne
+44 (0)20 3077 5700

Abcourt Mines is a research client of Edison Investment Research Limited

Note: PBT and EPS are normalised, excluding amortisation of acquired intangibles and exceptional items.

Year end Revenue (C$m) PBT (C$m) EPS (C$) DPS (C$) P/E (x) Yield (%)
6/24 0.3 (11.4) (0.02) 0.00 N/A N/A
6/25 0.0 (15.2) (0.02) 0.00 N/A N/A
6/26e 16.7 (32.9) (0.03) 0.00 N/A N/A
6/27e 97.7 (3.9) (0.01) 0.00 N/A N/A

Heading towards steady state in April 2027

Despite being constrained by the size of Abcourt’s workforce, ramp-up in terms of tonnes has been relatively close to Edison’s original forecast in April, with a shortfall of just 6.5% in August. However, there has been a concurrent decline in grade. While some of this decline could be attributed to mine sequencing and the processing of lower-grade material from development zones (typical of a transitional expansion phase in underground workings), some has been attributed to the blasting practices of a relatively inexperienced workforce. Management has put in place five mitigation policies to remediate the grade decline (see page 3), which began to bear fruit in August, with a 42.6% increase in grade relative to July and a 31.1% increase in tonnage, resulting in a 91.5% increase in gold produced. Consequently, we have extended our expectation of the attainment of steady-state operations (throughput of 10,642tpm at a head grade of 8.1g/t to produce c 2,680oz pm) from December 2026 to April 2027.

Valuation: Potentially still approaching C$1.00/share

Above a long-term gold price of US$3,500/oz we derive a value for Abcourt of at least 10.4c/share (see Exhibit 7). This increases by c 4.2c/share for every US$500/oz by which the gold price increases, and would reach 15.4c at a long-term gold price (approaching that at the time of writing) of US$4,119/oz. At this (higher) gold price, we estimate that Abcourt could generate c 7.2c per year in EPS, putting it on a forward P/E multiple of slightly less than one. Adding 4.5 years to Sleeping Giant’s life (management’s immediate, short-term target) adds c 80% to our valuation, to 28.5c/share. Adding 10 years to its life (which could be supported by resources, subject to confirmation drilling) approximately doubles the valuation to 39.5c/share. It then increases by a further 15.9%, to 45.7c/share, if we assume long-term cash flow per share growth of 4.1% post-FY31 (the same as the real-terms compound annual average increase in the gold price from 1967 to 2025). Under these circumstances, an investor purchasing Abcourt’s shares at C$0.07 could expect to earn an internal rate of return (IRR) of 36.5% on their investment in Canadian dollar terms over the next 15 years.

Background

Abcourt Mines is a Canadian exploration company with properties located in north-western Quebec. Its flagship asset is the Sleeping Giant (Geant Dormant) mine and mill, which comprises four mining leases, covering an area of over 458 hectares (ha) and 69 mining claims. Between 1988 and 2014, the complex produced 1.1Moz gold at an average grade of 10.24g/t and Abcourt is now in the process of returning Sleeping Giant to production. It also owns the Flordin and Barvue properties, where it is actively pursuing explorations, as well as the Elder mine and the Pershing-Manitou, Vendome, Aldermac and Jonpol properties.

Geology and mining

Spatially, the Sleeping Giant orebody may be conceived of as being in the shape of a rose, with the petals representing the stacked, mineralised lenses within the host rock and with the greatest concentration of mineralisation to be found in the centre of the structure. Often described as ‘complex’, the overall structure might be better described as ‘intricate’. Anecdotally, an observer may be reasonably certain that many stacked lenses exist. However, they are not regular (by geometrical standards) and so their precise location can only be determined by close-spaced definition drilling. To this end, Abcourt has an internal target of drilling 3,000m per month (which it first achieved in March and maintained in August) with the goal of delineating 300koz of economically mineralised material to mine at a rate of 30koz per year from the indicated category of resources only over 10 years.

The current depth of the mine is 1,200m, although Abcourt’s focus is on levels above c 400m while lower levels are being rehabilitated. However, exploration drilling has also intersected mineralisation above and below trend and below the shaft bottom. One of the reasons for the mine’s name is the supposition that a large, conventional volcanogenic massive sulphide system underlies the currently defined geology.

In due course, Abcourt intends to produce mined material at a rate of c 350tpd (c 10,600tpm), which will fill the mill to approximately 50% capacity. In general, the mining method is optimised to the deposit geometry, with steeper geometries (>40°) being mined by long-hole open stoping methods and shallower ones being mined using conventional room-and-pillar techniques.

Initially, output was exclusively from room-and-pillar stopes. However, Abcourt’s priority is now the development of much more productive long-hole stopes, the first of which was commissioned in April with a target of reaching steady-state production of c 10,600tpm as rapidly as possible.

Processing

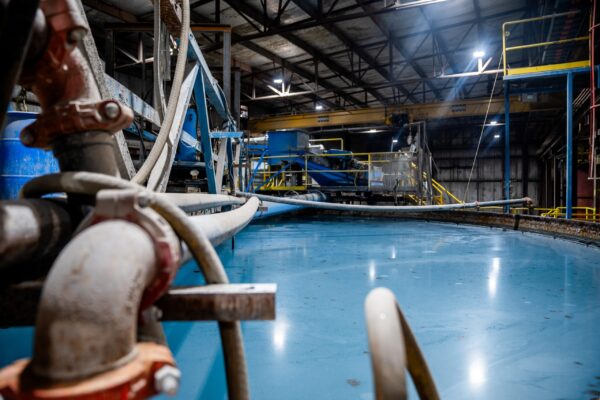
Ore is currently processed using two stages of crushing, rod mill grinding and ball mill grinding. Consistent with past practice, ore processing is via the carbon-in-pulp method (CIP), typically used in the Abitibi region. The capacity of the processing plant is c 800tpd (c 292,200tpa) and is approximately twice the currently expected rate of mined tonnage of 350tpd, based on a 12-hour daily shift pattern. Based on a model that was developed from mill performances when processing, metallurgical recovery is expected to stabilise at c 96.7%.

Ramp-up

Abcourt’s preliminary economic assessment (PEA), prepared by InnovExplo, assumed that production at Sleeping Giant would ramp up rapidly over the space of around three months (plus a further three months before commercial production was declared). In contrast, Edison assumed that it would ramp up over c 17 months, from August 2025 until December 2026, driven by the observation that output at Sleeping Giant is primarily constrained by the size of the workforce and the number of long-hole stops that Abcourt is able to bring into production. Since the re-start of mining in August 2025, production was initially from room-and-pillar stopes and the rate of ramp up was relatively slow. Within this context, the development of the drifts leading to the long-hole stopes has been a priority for Abcourt. The first long-hole stope was commissioned underground in April and was brought into production in the middle of the year.

Whereas production tonnes have largely ramped up in line with Edison’s initial expectations (Edison’s April forecast for tonnes milled in August was 6,642t compared to an actual outcome of 6,209t, ie only a 6.5% shortfall), there has been a noticeable decline in head grade. While some of this decline could be attributed to mine sequencing and the processing of lower-grade material from development zones (typical of a transitional expansion phase in underground workings), some has also been attributed to the blasting practices of a relatively inexperienced workforce. The variation of actual from forecast operational results can be seen by a comparison of Exhibits 1 and 2 (with the vertical lines denoting the boundary between past and future at the time they were created). In mitigation of the decline in grade:

  • Senior management has effectively relocated to the mine in order to drive the twin imperatives to expediting ramp-up at the same time as maintaining acceptable grade control.
  • Abcourt hired a further six miners in August (after hiring 42 in Q326) to take the total to 149 out of a target of 190 (ie 78% of full complement).
  • Abcourt instigated a training partnership with Technica, whereby two trainers are currently supervising 10 apprentice miners, with the objective of developing an internal pool of qualified workers.
  • It has concluded an official strategic partnership, such that it is now able to rapidly induct trainees from the Centre de formation professionnelle de la Baie-James (CFPBJ).
  • It has recruited a second shift team at the mill, thereby enabling day and night mill operations on a 4-3 schedule. This team optimisation will be fully operational this month (October) and will allow for a processing rate of up to 800tpd.

In response, Sleeping Giant’s head grade increased by 42.6% month-on-month in August relative to July. In conjunction with a 31.1% increase in tonnes milled, this resulted in a 91.5% increase in gold produced. Abcourt also revealed (23 September) that it had successfully hoisted 5,706t of ore and milled 4,761t in September so far, implying a pro rata hoisting rate of 7,443tpm and a pro rata milling rate of 6,210tpm for that month. Consequently, we have revised our ramp-up profile to that shown in Exhibit 2.

Updated assumptions

Sleeping Giant ramp up and subsequent mining schedule

In the first instance, our operational assumptions regarding Abcourt’s mining of the Sleeping Giant mine are derived from its June 2023 PEA, prepared by consultant InnovExplo (NB Abcourt intends to provide the market with an updated scoping study on the project in early CY27). This entails mining 720.2kt of material over seven years at an average rate of 126.5kt per (full) year, an average grade of 8.1g/t and an average metallurgical recovery rate of 96.7% to produce 181.4koz gold (c 30koz per year) at an initial capital cost of C$60.7m (plus C$31.8m in sustaining capex and closure costs) and opex of C$302.83/t. However, whereas the PEA assumed that ramp up would occur rapidly over the space of around three months (plus a further three months before commercial production was declared), Edison’s updated ramp-up profile now assumes that this will occur over about 20 months, from August 2025 until March 2027 (cf 17 months until December 2026 previously – see Exhibits 1 and 2). We assume that the gold price will remain at current levels until June 2027 (cf December 2026 previously), before reverting to our long-term price forecasts, as shown in the table below:

After June 2027, we assume that the mining schedule at Sleeping Giant will revert to that set out in InnovExplo’s June 2023 PEA and shown below:

Coupled with a metallurgical recovery of 96.7%, these profiles translate into gold production rising from 344oz in August to 2,680oz in April 2027, before stabilising at a rate of c 30koz per year from FY28:

Over the same timeframe, we expect unit costs to decline from an estimated C$1,298.75/t in Q326 to C$309.32/t in Q427 in an approximately straight line as tonnes increase and as mining efficiencies are achieved with an ever-more productive workforce.

Valuations and sensitivities

Edison’s valuation of single asset mining companies at pre-production stage is typically based on the value of dividends that a shareholder could expect to earn from their investment if they were to hold their shares from the moment of purchase until the end of the life of the mine, discounted to present value. Discretionary exploration investment is ordinarily excluded from our financial forecasts when this method is used, as it is presumed to be at least value adding.

Compared with the alternative discounted cash flow (DCF) method of analysis, the discounted dividend approach more purely reflects the returns that an equity shareholder may expect to receive. Hence, it is possible to calculate an IRR pertaining to an investment in a company’s equity at any particular share price and any particular point in time, rather than calculating an IRR for a project as a whole (which typically aggregates debt and equity returns and is therefore independent of a company’s share price). Being based on only one unit of measurement (forecast future dividends), it is also relatively simple to estimate a value (and hence share price) for a company at some point in the future in comparison with a DCF valuation, which typically requires three inputs (namely, forecast future cash flows, net debt/cash and minority ownership). However, in the case of Abcourt, we have decided to present both discounted dividend and DCF valuations in order to benefit from the latter’s ability to generate a terminal cash flow multiple to accommodate potential mine life extensions.

As noted previously, Edison’s valuations are initially conducted at an extremely conservative gold price of less than US$2,000/oz, a price that, while possible, we believe is becoming ever-less likely in the absence of major policy changes in the US (see: A note on the gold price, below). Of much greater importance is our valuation of Abcourt at something close to prevailing market conditions. As a result, in formulating our valuations of Abcourt, we have manipulated three parameters, namely:

  • The gold price.
  • The life of operations; this is performed by choosing FY31 (the final year of full-scale operations) as the ‘terminal’ year and then calculating the net present value (NPV) of cash flows (at Edison’s customary 10% discount rate), assuming Abcourt’s cash flow per share in FY31 is extended for an additional number of years. Note that, at a processing rate of 127.7ktpa, economic mineralised material is capable of supporting production for 5.6 years, but resources are capable of supporting production for 12.8 years. Abcourt’s short-term goal is to increase the mine life to a visible 10 years, which would require an additional 4.5-year extension relative to our ‘base case’.
  • The real terms price increase in the price of gold after FY31; in our initial consideration of mine life extensions, it is assumed that there is zero real-terms increase in the gold price in the additional years and that FY31’s cash flow per share extends unchanged into those years as well. In the alternative case, we have used 4.1% as a compound average annual growth rate, which is the long-term, real appreciation in the gold price from 1967 to 2025 (Exhibit 10) and is used as a proxy for cash flow per share growth after FY31 (note that this implicitly assumes growth in unit costs also of 4.1% per year).

Exhibit 7 shows Edison’s Abcourt valuation with respect to all of these parameters. It is immediately obvious, within the context of this analysis, that our valuation is most sensitive to the gold price, with each US$500/oz increase in the long-term price adding c 4.2c to the ‘base case’ valuation. Whatever the gold price scenario, adding 10 years to Sleeping Giant’s life more than doubles the valuation, while adding 4.5 years adds c 80%. However, thereafter, adding to the rate of cash flow per share growth rate post-FY31 has only an incremental effect on the valuation:

At the current gold price of US$4,119/oz, we estimate a discounted dividend valuation of Abcourt’s shares of 18.6c and a DCF valuation of 15.4c (both excluding discretionary exploration expenditure).

A note on the gold price

The average gold price in CY25 was US$3,445/oz (source: Bloomberg). Consistent with our general policy, our gold price forecast for CY26 now assumes that the current spot price of US$4,119/oz will prevail until June 2027 (cf December 2026 previously), before reverting to our long-term levels as follows:

The gold prices in Exhibit 8 are derived with respect to historical precedent. However, almost the only modern precedent to today’s market is that of 1970–81 when gold rose from its post-war currency peg of US$35/oz to a peak of US$850/oz in January 1980 before falling by more than 60% in the following two years. The analysis above implicitly assumes a repeat of the same pattern, with 2026 being an analogue to 1980 and 2027 being an analogue to 1981 etc. However, there are material differences between the two periods of time. The biggest is that, in 1980 the US was still the world’s largest creditor nation, and what suddenly reversed gold’s fortunes was the policy adopted by the then-new Federal Reserve chairman, Paul Volcker, to ‘defend the value of the US dollar’. That entailed sharply raising real interest rates from near zero to around 4% (among other things, causing a sharp recession in the US and most other western countries in the early 1980s), where they remained for most of the next two decades. However, now the US is the world’s largest debtor nation and neither the US administration nor the Federal Reserve is talking about defence of the dollar. In fact, quite the opposite: what is being talked about is allowing the dollar to find a level at which US exports can compete on world markets and stimulating the domestic economy with real interest rates as low as possible. Hence, all the forces that have pushed gold to its recent peak of over US$5,000/oz continue to prevail.

President Trump’s nomination of Kevin Warsh as chairman of the Federal Reserve appeared to be the catalyst for the start of gold’s sell-off from its recent record highs since March. He is reported to be in alignment with Trump in wanting to shrink the Fed’s balance sheet at the same time as cutting rates dramatically, thus effectively steepening the yield curve. In themselves, neither a steepening of the yield curve nor cuts to the Fed’s balance sheet are traditionally positive harbingers for gold. However, lower short-term rates (and lower short-term real rates, in particular) are potentially positive. In order to make bank reserves currently deposited with the Federal Reserve available for investment in Treasuries, Warsh is assumed to be contemplating redefining inflation in such a manner as to obviate the traditional interest-rate response, with a focus on trend rates, rather than the specific rate at any particular point in time. Notwithstanding the recent quarter point increase in the Fed funds rate and short-term market expectations, in the medium to longer term, this should allow him to reduce (or maintain at lower levels) short-term interest rates even in circumstances in which inflation appears (temporarily) elevated, as long as the longer-term trend rate remains consistent with the target rate at some point in the future. In theory, this could stimulate a reallocation of bank reserves into longer-dated Treasuries. At the same time, management of the long end by means of a relaxation of the supplementary leverage ratio could limit the degree of steepening (and thereby rein in the cost of borrowing for the federal government).

However, it remains to be seen whether cuts to short-term interest rates under a new Treasury-Fed accord can be achieved without reigniting inflation and whether the markets can be convinced that any apparent increase in prices is transient, rather than embedded. Either way, it appears likely that a period of heightened inflation beckons and much will depend on whether investors believe that the Federal Reserve will want to be seen to react hawkishly or to accept the risk of Warsh’s new, but relatively untested, theory. Currently, the market seems to be assuming that a hawkish response is inevitable, and, hence, increases in inflation appear to correlate to increased interest-rate expectations and a lower gold price. However, this knee-jerk reaction may abate. In recent testimony, Warsh vowed to deliver price stability at the same time as saying that he had ‘no preferred inflation measure’. As such, the Fed may ultimately come to be seen as a dove in hawk’s plumage. In the meantime, neither short-term real interest rates of 0.475% (a Fed Funds rate of 3.75–4.00% minus inflation of 3.4%) nor long-term real interest rates of 2.218% are attractive relative to gold’s compound average annual growth rate of 4.1% in real terms since 1967 (see Exhibits 9 and 10). If nothing else, this will continue to encourage holders of dollars (especially the world’s central banks) to convert them into gold – a trend that appears to have reasserted itself after a brief, liquidity-driven interruption in March, at the start of the Iran war.

While it is tempting to look at recent graphs of the gold price and attempt to call a ‘top’, investors should beware as many of the forces that drive it are often self-reinforcing, especially the fact that above-ground stocks of gold of c 216,000 tonnes dwarf newly mined supply of c 3,700 tonnes per year. Hence, traditional supply and demand analysis often fails in the case of gold, where price discovery tends to occur among existing holders, rather than new buyers and sellers. This means, while the price has appreciated substantially (eg from below US$1,300/oz in May 2019), in the absence of a fundamental shift in macroeconomic policy, there is no reason to suppose that it cannot continue much higher. The following demonstrates the extent to which this is possible:

  • The gold price required to cover the total US monetary base is US$20,693/oz (based on August’s number). This is analogous to the classical gold standard, according to which the Federal Reserve was required to hold enough gold to redeem all of its liabilities (ie US dollars) that could be in circulation. Although President Nixon formally closed this dollar window in August 1971, in the era of a floating gold price, US gold reserves were nevertheless still able to cover the US total monetary base as recently as 1980.
  • The US net international investment position (the difference between its external financial assets and its external liabilities – historically conceived of as being the sum of past current account deficits) has recently been revised downwards quite substantially, from a net deficit of US$27.54tn, to one of US$21.27tn (nevertheless, still c 66% of GDP). As a result, the gold price required to cover the US net international investment position has also fallen from more than US$100,000/oz to US$85,564/oz. Nevertheless, this number is what would theoretically be required to enable the US to cover all of its accumulated deficits since c 1979 with its gold reserve.
  • The gold price required to cover both the US net international investment position and its monetary base is thus US$106,257/oz.

While gold would need to increase c 25 times to get from its level now to US$106,257/oz, it is perhaps worth noting that it has already gone up by 119 times to get from its level of US$35/oz in 1967 to its current price and by over 16 times since as recently as 2001. Inevitably, few guarantees can be made regarding the future evolution of the world economy. However, the following conjectural sequence of events may demonstrate a mechanism by which these price levels could be achieved:

  • First, the gold price reaches a level of US$20,6933/oz, which fully covers the total US monetary base and is therefore comparable to the levels that it reached in 1980. At the current forex rate of CNY6.7060/US$ this would equate to a renminbi price of gold of CNY138,767/oz.
  • At the current time, US GDP per capita is US$94,430 according to the International Monetary Fund, while China’s is CNY95,749 per capita, which equates to c US$14,278 per capita at the current exchange rate.
  • The Chinese renminbi then appreciates from CNY6.7060/US$ to near parity in the ensuing years (see paragraph below for sterling-dollar precedent). In this case, the renminbi price of gold needs only to be maintained at a flat CNY138,767/oz in order for the US dollar price of gold to reach US$138,767/oz (NB to reach US$106,257/oz the renminbi would only need to appreciate to CNY1.3060/ US$).
  • At this point in time, not only would the US dollar gold price have reached the levels required to balance its negative net international investment position (as above), but Chinese GDP per capita would have increased to match that of the US. At some point in time, therefore, we think that it is likely that the People’s Bank of China will abandon its currency peg to preserve its citizens’ wealth as well as to manage the transition of China’s workers from global producers to global consumers, albeit at the cost of accepting a much more competitive US dollar in world markets.

As a precedent to the above, we would point to the fact that the UK was the world’s largest creditor nation prior to 1914 (akin to the US in 1980). At that time, the price of gold was £4.4s.11½d per ounce (effectively £4.25/oz in decimalised currency) and US$20.67 per ounce, such that the sterling-dollar (cable) rate was US$4.86/£. After sterling came off the gold standard in 1931 and the US devalued, this rate peaked at just over US$5.00/£ in 1934 during a rush to safety into the world’s reserve currency (ie sterling). By 1945, the UK had become the world’s largest debtor nation (c 15–25% of GDP), and, in just 40 years, sterling would test parity against the dollar in February/March 1985 (and then again in September 2022). The US, by contrast, became the world’s largest debtor nation in 1990, in which case a similar 40-year gap would suggest that it could test parity with the renminbi as early as 2030. A further 37-year gap could see this extended to 2067.

Official financial agencies do not publish a single country’s share of the US net international investment position, as complex corporate structures often make it difficult to determine the ultimate beneficial owners of diverse financial instruments. However, analysing the primary, tangible data components tracked by the US Department of the Treasury and the Bureau of Economic Analysis, China may be estimated to own c 3–6% (c US$3tn) of total foreign-owned assets in the US, while the US may be estimated to own c US$1tn in assets in China, to give the US a net international investment liability of US$2tn at current forex rates. To balance this position would therefore only require the renminbi to move from its current rate of CNY6.7060/US$ to CNY2.2353/US$ (in which case, the gold price would reach a level of US$62,080/oz in the framework outlined above).

As stated previously, few guarantees can be made regarding the future evolution of the world economy. Agreements similar to the 1985 Plaza Accord may attempt to manage global foreign exchange rates in an orderly fashion. However, the numbers calculated demonstrate the extent to which the world has financialised since 1971 to the detriment of real assets. At the same time, this analysis demonstrates that, in the absence of a major policy change from either China or the US, in particular, the bull market for gold may be very far from over.

General disclaimer and copyright

This report has been commissioned by Abcourt Mines and prepared and issued by Edison, in consideration of a fee payable by Abcourt Mines. Edison Investment Research standard fees are £60,000 pa for the production and broad dissemination of a detailed note (Outlook) following by regular (typically quarterly) update notes. Fees are paid upfront in cash without recourse. Edison may seek additional fees for the provision of roadshows and related IR services for the client but does not get remunerated for any investment banking services. We never take payment in stock, options or warrants for any of our services.

Accuracy of content: All information used in the publication of this report has been compiled from publicly available sources that are believed to be reliable, however we do not guarantee the accuracy or completeness of this report and have not sought for this information to be independently verified. Opinions contained in this report represent those of the research department of Edison at the time of publication. Forward-looking information or statements in this report contain information that is based on assumptions, forecasts of future results, estimates of amounts not yet determinable, and therefore involve known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of their subject matter to be materially different from current expectations.

Exclusion of Liability: To the fullest extent allowed by law, Edison shall not be liable for any direct, indirect or consequential losses, loss of profits, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note.

No personalised advice: The information that we provide should not be construed in any manner whatsoever as, personalised advice. Also, the information provided by us should not be construed by any subscriber or prospective subscriber as Edison’s solicitation to effect, or attempt to effect, any transaction in a security. The securities described in the report may not be eligible for sale in all jurisdictions or to certain categories of investors.

Investment in securities mentioned: Edison has a restrictive policy relating to personal dealing and conflicts of interest. Edison Group does not conduct any investment business and, accordingly, does not itself hold any positions in the securities mentioned in this report. However, the respective directors, officers, employees and contractors of Edison may have a position in any or related securities mentioned in this report, subject to Edison's policies on personal dealing and conflicts of interest.

Copyright 2026 Edison Investment Research Limited (Edison).

Australia

Edison Investment Research Pty Ltd (Edison AU) is the Australian subsidiary of Edison. Edison AU is a Corporate Authorised Representative (1252501) of Crown Wealth Group Pty Ltd who holds an Australian Financial Services Licence (Number: 494274). This research is issued in Australia by Edison AU and any access to it, is intended only for "wholesale clients" within the meaning of the Corporations Act 2001 of Australia. Any advice given by Edison AU is general advice only and does not take into account your personal circumstances, needs or objectives. You should, before acting on this advice, consider the appropriateness of the advice, having regard to your objectives, financial situation and needs. If our advice relates to the acquisition, or possible acquisition, of a particular financial product you should read any relevant Product Disclosure Statement or like instrument.

New Zealand

The research in this document is intended for New Zealand resident professional financial advisers or brokers (for use in their roles as financial advisers or brokers) and habitual investors who are “wholesale clients” for the purpose of the Financial Advisers Act 2008 (FAA) (as described in sections 5(c) (1)(a), (b) and (c) of the FAA). This is not a solicitation or inducement to buy, sell, subscribe, or underwrite any securities mentioned or in the topic of this document. For the purpose of the FAA, the content of this report is of a general nature, is intended as a source of general information only and is not intended to constitute a recommendation or opinion in relation to acquiring or disposing (including refraining from acquiring or disposing) of securities. The distribution of this document is not a “personalised service” and, to the extent that it contains any financial advice, is intended only as a “class service” provided by Edison within the meaning of the FAA (i.e. without taking into account the particular financial situation or goals of any person). As such, it should not be relied upon in making an investment decision.

United Kingdom

This document is prepared and provided by Edison for information purposes only and should not be construed as an offer or sol icitation for investment in any securities mentioned or in the topic of this document. A marketing communication under FCA Rules, this document has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.

This Communication is being distributed in the United Kingdom and is directed only at (i) persons having professional experience in matters relating to investments, i.e. investment professionals within the meaning of Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, as amended (the "FPO") (ii) high net-worth companies, unincorporated associations or other bodies within the meaning of Article 49 of the FPO and (iii) persons to whom it is otherwise lawful to distribute it. The investment or investment activity to which this document relates is available only to such persons. It is not intended that this document be distributed or passed on, directly or indirectly, to any other class of persons and in any event and under no circumstances should persons of any other description rely on or act upon the contents of this document.

This Communication is being supplied to you solely for your information and may not be reproduced by, further distributed to or published in whole or in part by, any other person.

United States

Edison relies upon the "publishers' exclusion" from the definition of investment adviser under Section 202(a)(11) of the Investment Advisers Act of 1940 and corresponding state securities laws. This report is a bona fide publication of general and regular circulation offering impersonal investment-related advice, not tailored to a specific investment portfolio or the needs of current and/or prospective subscribers. As such, Edison does not offer or provide personal advice and the research provided is for informational purposes only. No mention of a particular security in this report constitutes a recommendation to buy, sell or hold that or any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.

London │ New York │ Frankfurt

20 Red Lion Street

London, WC1R 4PS

United Kingdom

More on Abcourt Mines

View All

Metals & Mining

Abcourt Mines — Production ramp-up latest

Metals & Mining

Abcourt Mines — Sleeping no more

Latest from the Metals & Mining sector

View All Metals & Mining content

Research: Consumer

Global Fashion Group — The reset is delivering

Global Fashion Group (GFG) operates online fashion and lifestyle platforms in Australia and New Zealand, Latin America and South-East Asia. Over the last three years, management has substantially reshaped the businesses following the post-pandemic downturn. Geographic exposure has been narrowed, product ranges have been curated, inventory has been reduced and marketing has moved away from chasing volume towards attracting and retaining customers that are likely to generate an acceptable return. Although the three regions are now at different stages of recovery, most importantly they are all now profitable based on adjusted EBITDA. Management is therefore increasingly moving from restructuring the businesses to demonstrating the profitability and cash generation the revised model can deliver. A rating more in line with peers indicates the current share price should be worth more than double its current level, and even higher if profitability improves.

Continue Reading
Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.