Sparks commentary - Shepherd Neame

Consumer

Sparks - Shepherd Neame

More on this equity
Shepherd Neame (AQSE:SHEP) brewery transformation to improve returns
Published by Russell Pointon

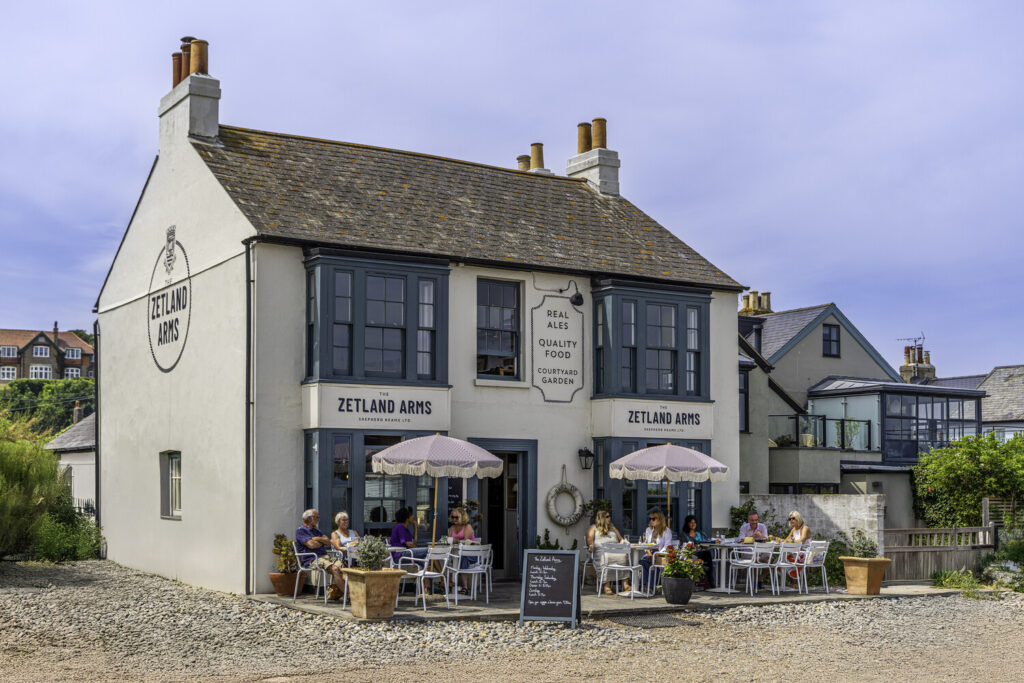
Shepherd Neame has announced a significant strategic transformation of its brewing operations, alongside a reassuring AGM trading update. The company plans to invest £15m over three years in a modern, smaller brewery at its historic Faversham site, focusing on its own brands and exiting large third-party brewing contracts. The investment, expected to be funded through non-core property disposals, should improve operational efficiency and long-term returns in a division that has faced sustained profitability pressures. Meanwhile, pub trading remains encouraging, with retail like-for-like sales up 6.4% in the first 17 weeks of FY27. The combination of a more focused brewing operation and sustained investment in the pub estate provides a clearer route to improved returns, with management anticipating no change to FY27 market expectations.

Having highlighted a review of the Brewing and Brands division at the FY26 results, the proposed investment represents an important step in its repositioning. The division generated just £0.1m of underlying operating profit in FY26, compared with £1.0m in FY25, reflecting declining volumes and rising logistics costs. The new facility will be developed within the existing Bottling Hall, which will close in mid-2027, with completion targeted by the end of 2029. The revised operating model will combine in-house brewing with selected outsourced functions, including small packaging, while retaining the existing own-brand portfolio. The company will discontinue its large third-party brewing contracts, including its Singha licence, which expires in April 2027 and currently accounts for £10.3m of annual revenue. Although this will reduce reported revenue, the strategic shift towards higher-value own-brand production should support improved profitability and capital efficiency over time. Further details of the wider review of the division are expected in due course.

Current trading continues to demonstrate good momentum. Retail like-for-like sales increased 6.4% in the 17 weeks to 24 October 2026, following growth of 6.7% in the first 13 weeks, while tenanted like-for-like income increased 1.1% to 26 September versus 0.4% in the 9 weeks to 29 August. Beer volumes have softened, with total volumes declining 0.6% and own beer volumes falling 2.2% over the 17-week period. These follow growth in the first 13 weeks of the year. Trading remains underpinned by the company’s continued investment in its strongest pub assets, particularly in London.

Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.