Orell Fussli — Banknotes, books – and don’t forget your ID

Orell Fussli (SIX: OFN)

Last close As at 04/11/2026

CHF140.00

▲ 1.00 (0.72%)

Market capitalisation

CHF273m

More on this equity

Research: Industrials

Orell Fussli — Banknotes, books – and don’t forget your ID

Orell Füssli’s execution remains consistent with its FY28 targets, including revenue of CHF300m and EBIT margins of 8.5–9.5%. H126 results were in line with management’s expectations. Security Printing capacity utilisation is expected to remain high into 2027 while Book Retailing continues to expand, driven by management’s careful approach to footprint expansion. Having won two contracts, Procivis (digital credentials) is seeing rising enquiries, participating in numerous tenders and offering exciting future potential. Our updated valuation of CHF151/share offers c 9% upside.

Written by

Jonathan Day

Director of Content, Industrials

six logo

Industrials

Progress review

5 November 2026

Price CHF138.00
Market cap CHF270m

Net cash/(debt) as at 30 June 2026

CHF52.8m

Shares in issue

2.0m
Free float 41.7%
Code OFN
Primary exchange SWX
Secondary exchange N/A
Price Performance

Business description

Orell Füssli was founded in Zurich in 1519 and is today an international listed company active in the fields of security printing and technology, book retailing and publishing.

Analyst

Jonathan Day
+44 (0)20 3077 5700

Orell Füssli is a research client of Edison Investment Research Limited

Note: EBIT, PBT and diluted EPS are on a company reported basis.

Year end Revenue (CHFm) EBIT (CHFm) PBT (CHFm) EPS (CHF) DPS (CHF) P/E (x) Yield (%)
12/24 252.5 22.6 21.7 7.19 4.40 19.2 3.2
12/25 272.8 29.2 29.9 9.69 5.80 14.2 4.2
12/26e 281.5 25.4 24.8 9.42 6.09 14.6 4.4
12/27e 294.9 29.2 28.6 10.85 6.39 12.7 4.6

Execution remains on track

Orell Füssli reported H126 results that were in line with management’s expectations and demonstrated progress across the divisions, with Security Printing and Zeiser experiencing high capacity utilisation, which the company expects to continue into 2027. Book Retailing saw continued expansion of the store portfolio, while Procivis participated in numerous tenders, with high enquiries supported by forthcoming EU regulation. FY26 guidance for 2–5% revenue growth and an EBIT margin of around 9% was unchanged, implying a seasonal improvement in H2 consistent with historical trends, including the timing of back-to-school and Christmas retailing.

2028 targets well underpinned

The progress demonstrated so far this year illustrates that the long-term trends highlighted by Orell Füssli at its November 2025 capital markets day (CMD) remain intact. Growth in banknotes in circulation of c 3.5% per year since 2019 and 5.6% per year since December 2004, driven by population growth, GDP, inflation and clean note policies, supports the high-margin Security Printing division and Zeiser. Careful store portfolio additions in high-footfall locations and an omnichannel strategy drive Book Retailing, while the pending requirement for EU citizens to have digital credentials provides growth optionality for Procivis, with the enterprise sector also representing a large longer-term opportunity. Growth drivers plus efficiency and operating leverage underpin our FY28 forecasts for revenue of CHF307m and EBIT of CHF30.8m, implying an EBIT margin of 10.0% with strategic targets achieved.

Updated SOTP valuation supports CHF151/share

We make minor changes to our estimates and update our SOTP valuation, retaining our existing methodology. Lower peer valuations are the primary driver behind our CHF151/share valuation (CHF181 previously), which is now determined using 2027 as our base year (2026 previously) and offers almost 9% upside. The company continues to trade at an undemanding 12.7x FY27e P/E multiple with a 4.6% yield and a strong balance sheet. Risks include weaker consumer sentiment, Procivis execution risk and the impact of digitisation on Security Printing.

Investment summary

Orell Füssli is a pioneer in the fields of security, education and digital credentials. The company was founded in Zurich in 1519 and is today an international listed company active in the fields of security printing and technology, book retailing and publishing. We believe the company is on track to achieve its FY28 targets: revenue of CHF300m, an 8.5–9.5% EBIT margin and a 60–80% dividend payout ratio. Security Printing is a high-margin business with high capacity utilisation that management expects to continue into FY27. We expect Book Retailing to continue to grow, supported by management’s careful footprint expansion, while the Procivis digital credentials activities provide an exciting option for future growth, supported by regulation, early contract wins and high enquiry levels. We expect the balance sheet to remain in a net cash position as management continues with its conservative approach. Our unchanged sum-of-the-parts (SOTP) valuation methodology suggests CHF151 per share, implying upside of c 9%.

On track for 2028

At its CMD on 11 November 2025, Orell Füssli maintained clear revenue, profitability and dividend targets (introduced in 2022) for FY28:

  • CHF300m in sales;
  • an 8% EBIT margin (upgraded in March 2026 to 8.5–9.5%); and
  • a 60–80% dividend payout ratio.

Longer-term sales growth is seen at 4–6% per year underpinned by the company’s Perform (operational excellence/efficiency in the core business driving 2–3% annual sales growth), Create (2–3% additional revenue from innovative products and services), Invest (CHF30–50m new sales from new companies/technology/markets) framework.

Orell Füssli reports revenue under four main business areas (see Exhibit 1).

Security Printing and Book Retailing accounted for the majority of FY25 revenues, while Security Printing accounts for the largest proportion of operating profit (FY25: 73%) due to significantly higher margins (see Exhibit 4).

In March 2026, Orell Füssli reported strong FY25 results and introduced FY26 guidance for sales growth of 2–5% and an EBIT margin of around 9%, supported by management’s expectations for high capacity utilisation in Security Printing until 2027 due to a solid order book but with a slightly softer mix. At the same time, the company raised FY28 margin guidance to 8.5–9.5%.

H126 results in line, unchanged guidance

H126 results were in line with management’s expectations and showed progress across the divisions. Group revenue of CHF121.4m was up 1% y-o-y (H125: CHF120.1m).

Security Printing and Zeiser both operated at high capacity in H1. A change in product mix in the Security Printing division led to a lower operating result with adjusted EBIT of CHF6.9m, down c 32% y-o-y and the EBIT margin falling by 290bp to 5.6% from 8.5% in H125. The divisional performance was consistent with the outlook given with the FY25 results (good capacity utilisation, softer mix).

Book Retailing opened three new stores in H1 and Orell Füssli Thalia acquired 100% of the shares in A. Köhler, which operates 13 stationery stores in the cantons of Zurich, St Gallen and Schwyz. The acquisition creates a foundation for the long-term development of Köhler stationery stores as a specialist retailer. The stores will continue to operate under the Köhler brand and become additional collection points for online orders. In Publishing, Orell Füssli has consolidated its activities into Orell Füssli Verlage, where it will continue to operate under its well-established brands.

Orell Füssli’s digital credentials business, Procivis, participated in numerous tenders and was awarded two contracts. The division is seeing a strong increase in enquiries, driven by the introduction of new regulation in the EU that requires citizens to have a digital ID wallet (EUDI wallet) by the end of 2026, although Orell Füssli notes that implementation is lagging behind regulatory requirements, with the introduction of e-ID in Switzerland delayed again.

Despite the H126 weakness, the company expects a stronger H226 due to seasonally higher publishing revenues linked to the August start of the school year, Christmas book retailing and Zeiser deliveries from H126 order wins. Expectations for subdued economic growth and slightly weaker consumer sentiment in Switzerland were noticeable in Book Retailing, while geopolitical tensions unsettled the international business, with projects in the Gulf region postponed from H1 and now expected by the company to go ahead in H226.

FY26 guidance was unchanged from March 2026: Orell Füssli continues to expect revenue growth of 2–5%, slightly below the 4–6% long-term target range, an EBIT margin of around 9% and to remain on track to achieve its 2028 strategic goals (CHF300m revenue, EBIT margin 8.5–9.5%).

2028 targets well underpinned

The long-term trends highlighted by Orell Füssli, which support its 2028 targets, remain intact, supported by its Perform (operational excellence/efficiency in the core business driving 2–3% annual sales growth), Create (2–3% additional revenue from innovative products and services), Invest (CHF30–50m new sales from new companies/technology/markets) framework.

Security Printing and Industrial Systems

Banknotes in circulation across the EU continue to grow, driven by a number of trends:

  • a growing population;
  • growth of economic output (GDP);
  • central banks’ clean note policies (dirty or damaged notes are removed from circulation and replaced);
  • inflation; and
  • lack of personal bank accounts in many emerging markets (provides scope for growth).

In Exhibit 5 below we show EU data for the number of banknotes in circulation from December 2004 to September 2026. The CAGR over the period of 5.6% per year represents an increase in the number of banknotes in circulation from c 500m to more than 1.6bn. From 31 December 2019 until 30 September 2026 the growth rate was slower at 3.5% per year. While there was a dip following the COVID-19 pandemic, banknote growth appears to have resumed its long-term trajectory. While we forecast an 8% decline in Security Printing revenue this year (after 15% growth in 2025) due to the timing of a contract that was brought forward to Q425 from Q126 – an issue that has been well flagged by management – we forecast a recovery to 5% revenue growth in 2027 as timing issues drop out, with a more conservative 3% revenue growth in 2028. In line with management guidance, we expect high capacity utilisation to support revenue growth in 2027. Banknote demand is coming from regions including Africa, Latin America and parts of Asia. While capacity utilisation is high, management has a careful approach to capital allocation, and therefore we believe it is unlikely to expand capacity.

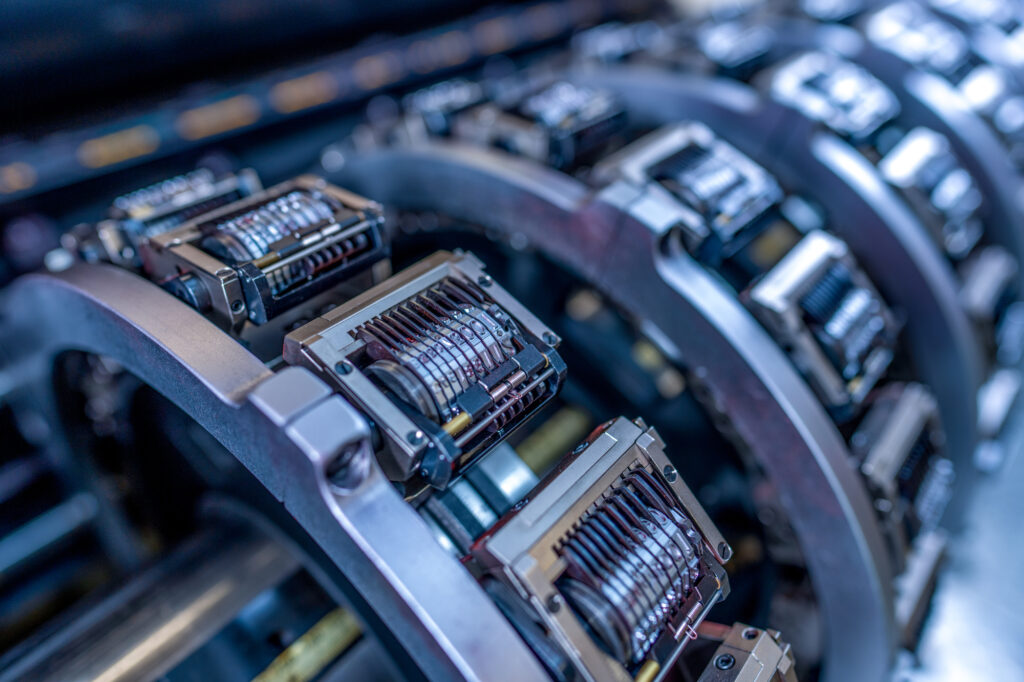
Orell Füssli is perhaps uniquely positioned given the reputation of Switzerland, its home market, for security and quality and the company’s 500-year history. Its largest shareholder is the Swiss National Bank, which owns around a third of Orell Füssli’s issued share capital and is also one of its major banknote customers. This in isolation is a clear indication of the high quality of its print capability. Furthermore, banknote printing is an industry with very high barriers to entry, given the technical complexity of the high-quality paper, detail and security features needed and the banknote serial numbers required.

Management notes that Zeiser (Industrial Systems) also ran at full speed in H126. Given the slower long-term growth rate of this division, we forecast 2% revenue growth in FY26, FY27 and FY28. Given the size of the division (9% of 2025 sales), it does not have a big impact on group forecasts.

Orell Füssli’s Security Printing and Industrial Systems divisions are also well placed to benefit from growth in markets such as identification and visa documents, driven by increased international travel, evolving government regulations and greater inclusion of biometric data into ID documents. The company has a track record of innovation, including proprietary Banknote Environmental Evaluation Software, which allows central banks to model and assess the environmental impact of any given physical or security characteristic of a note at the design stage. Zeiser is increasing its capabilities to enhance the transparency and traceability of security documents and is well positioned in its niche, which includes mechanical and electromechanical components for security printing machines as well as software for tracking and tracing documents in the production process. Operational excellence remains a consistent focus for management through to 2028, including initiatives such as improved information systems and more efficient software development.

Book Retailing and Education

Book Retailing is Orell Füssli’s biggest division by revenue and has seen the strongest revenue growth in recent years, supported by careful expansion of the branch network and further strengthening of market leadership in both brick-and-mortar and online channels, with a number one position in Switzerland in both B2B and B2C.

The market for Orell Füssli is split into two sections: publishing, which is the smaller market and where the company enjoys a c 13% market share in the Learning Media sub-sector, and distribution (retailing), which is a significantly bigger business when measured by revenue. Orell Füssli, via Orell Füssli Thalia (a 50%-owned joint venture), is the biggest book retailer in the German-speaking region of Switzerland, with over 60 locations, and also has stationery retail activities that have been expanded via the complementary acquisition of 100% of A. Köhler in H126, which brought 13 stationery stores to the portfolio. While the business is dependent on consumer sentiment, which the company describes as being weak, management has targeted high-frequency urban areas and transport hubs for its store portfolio and has maintained a fresh concept with smaller sales areas combined with cafes, events and curated assortments. We expect management to continue to successfully grow the footprint selectively, which, along with accelerated e-commerce, could be a source of upside to divisional revenues in future years. We note management’s confidence in continued market share gains.

Given the solid historical revenue growth, we forecast 10% revenue growth for the division in 2026, driven by both organic and inorganic growth. For FY27 and FY28 we forecast 5% revenue growth, which is below the 2020–26 CAGR of 6.6%.

Procivis: Don’t forget your ID

Procivis is Orell Füssli’s nascent digital identities and credentials business. It is developing and offering services that would allow traditional paper and physical identities and documents (such as identity cards and driving licences) to be held on an individual’s mobile device, meaning they can be used seamlessly in everyday situations to improve efficiency of transactions and reduce fraud. Data from the company’s November 2025 CMD showed an anticipated growth rate of c 20%.

Procivis One is the product that has been developed by Procivis to address this rapidly growing market. It has been specifically developed with an open architecture structure to allow for compatibility with different technology stacks in different regions and locations, for example Switzerland, the EU and the US.


As of H126, Procivis is participating in numerous tenders and has been awarded two contracts. Management noted at H126 that enquiries are up sharply, driven by the implementation of the eIDAS 2.0 Regulation in the EU that requires all 27 member states to offer a digital wallet to citizens by the end of 2026. We believe Procivis is well positioned to benefit from potential commercial opportunities in digital credentials, and we are encouraged by the increased enquiries and tender participation. While the timeline has shifted somewhat to the right, Procivis remains a potential source of upside for Orell Füssli over a five-year horizon, driven by both government contracts and the bigger corporate solutions market.

Seasonality

The retailing activities and exposure to education within publishing (Exhibit 1) introduce an element of seasonality to Orell Füssli’s business, with Christmas a strong period for retailing and back-to-school and education book purchasing concentrated in H2. This seasonal pattern is visible this year, and we show in Exhibit 11 management’s slide from the CMD and note that there were no changes to 2026 guidance at H1. In our opinion, management has a conservative track record and we therefore expect seasonality to be incorporated into guidance.

We expect 2028 targets to be achieved

We believe Orell Füssli is well positioned to achieve its FY28 targets given the drivers outlined above and the robust progress the company has delivered in recent years, reflected in both revenue growth and operating margin improvement. The latter has enabled management to raise FY28 margin guidance to 8.5–9.5%, and we expect this to be exceeded, driven by operating leverage (Exhibit 12), which is broadly consistent with recent levels. 2025 and 2026 data is distorted by the impact of the Security Printing contract pulled forward from 2026 into 2025. The company has a good track record of capital allocation. The balance sheet remains robust with a solid net cash position, which we expect to be broadly maintained.

Changes to estimates

We make minimal changes to our forecasts and include FY28 estimates in the table below. We believe the company is on track to achieve its FY28 targets, supported by the progress and drivers outlined above.

Performance and valuation, updated SOTP CHF151/share

Orell Füssli’s shares have delivered solid gains since January 2025, when the share price was around CHF77. The shares peaked at c CHF170 in May 2026 and have since given up some gains, bringing them back to the current level of around CHF140 (Exhibit 15). In Exhibit 16, we show Orell Füssli’s 12-month forward P/E ratio and the average since 1 January 2022 (13.75x), which illustrates the multiple expansion to almost 17x associated with the share price highs in May 2026, since when the forward P/E has contracted. Based on LSEG Data & Analytics data, the 12-month forward P/E of 12.9x is about 6% below the average. We take the average since 2022 to avoid the volatility associated with the pandemic, which we believe is less representative. Our FY27e P/E of 12.7x represents a c 8% discount to the average since 2022.

Updated SOTP valuation suggests CHF151 per share

Our unchanged SOTP methodology (Exhibit 17) suggests a valuation of CHF151/share compared to CHF181/share in our March 2026 note. We now use FY27 estimates instead of FY26 given that there are only roughly two months of 2026 remaining, and we believe FY27 is more appropriate. Peer multiples (Exhibit 18) have changed significantly since March, and this explains the majority of the change in our SOTP. Security Printing’s peer multiple has fallen to 9.9x from 13.0x and this division accounts for the largest proportion of EBIT (Exhibit 3) given its high margins (Exhibit 4). The peer multiple for Industrial Systems has contracted from 8.0x to 6.5x, while the peer multiple for Book Retailing has expanded to 17.3x from 12.7x. We maintain our 20% conglomerate discount. The resulting CHF151/share valuation implies c 9% upside.

Risks

Orell Füssli is exposed to a number of risks, including a potential decline in security printing activity if digitalisation replaces physical currency, weak consumer sentiment in book retailing, M&A risk associated with potential footprint expansion and execution risk related to the development of Procivis.

General disclaimer and copyright

This report has been commissioned by Orell Füssli and prepared and issued by Edison, in consideration of a fee payable by Orell Füssli. Edison Investment Research standard fees are £60,000 pa for the production and broad dissemination of a detailed note (Outlook) following by regular (typically quarterly) update notes. Fees are paid upfront in cash without recourse. Edison may seek additional fees for the provision of roadshows and related IR services for the client but does not get remunerated for any investment banking services. We never take payment in stock, options or warrants for any of our services.

Accuracy of content: All information used in the publication of this report has been compiled from publicly available sources that are believed to be reliable, however we do not guarantee the accuracy or completeness of this report and have not sought for this information to be independently verified. Opinions contained in this report represent those of the research department of Edison at the time of publication. Forward-looking information or statements in this report contain information that is based on assumptions, forecasts of future results, estimates of amounts not yet determinable, and therefore involve known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of their subject matter to be materially different from current expectations.

Exclusion of Liability: To the fullest extent allowed by law, Edison shall not be liable for any direct, indirect or consequential losses, loss of profits, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note.

No personalised advice: The information that we provide should not be construed in any manner whatsoever as, personalised advice. Also, the information provided by us should not be construed by any subscriber or prospective subscriber as Edison’s solicitation to effect, or attempt to effect, any transaction in a security. The securities described in the report may not be eligible for sale in all jurisdictions or to certain categories of investors.

Investment in securities mentioned: Edison has a restrictive policy relating to personal dealing and conflicts of interest. Edison Group does not conduct any investment business and, accordingly, does not itself hold any positions in the securities mentioned in this report. However, the respective directors, officers, employees and contractors of Edison may have a position in any or related securities mentioned in this report, subject to Edison's policies on personal dealing and conflicts of interest.

Copyright 2026 Edison Investment Research Limited (Edison).

Australia

Edison Investment Research Pty Ltd (Edison AU) is the Australian subsidiary of Edison. Edison AU is a Corporate Authorised Representative (1252501) of Crown Wealth Group Pty Ltd who holds an Australian Financial Services Licence (Number: 494274). This research is issued in Australia by Edison AU and any access to it, is intended only for "wholesale clients" within the meaning of the Corporations Act 2001 of Australia. Any advice given by Edison AU is general advice only and does not take into account your personal circumstances, needs or objectives. You should, before acting on this advice, consider the appropriateness of the advice, having regard to your objectives, financial situation and needs. If our advice relates to the acquisition, or possible acquisition, of a particular financial product you should read any relevant Product Disclosure Statement or like instrument.

New Zealand

The research in this document is intended for New Zealand resident professional financial advisers or brokers (for use in their roles as financial advisers or brokers) and habitual investors who are “wholesale clients” for the purpose of the Financial Advisers Act 2008 (FAA) (as described in sections 5(c) (1)(a), (b) and (c) of the FAA). This is not a solicitation or inducement to buy, sell, subscribe, or underwrite any securities mentioned or in the topic of this document. For the purpose of the FAA, the content of this report is of a general nature, is intended as a source of general information only and is not intended to constitute a recommendation or opinion in relation to acquiring or disposing (including refraining from acquiring or disposing) of securities. The distribution of this document is not a “personalised service” and, to the extent that it contains any financial advice, is intended only as a “class service” provided by Edison within the meaning of the FAA (i.e. without taking into account the particular financial situation or goals of any person). As such, it should not be relied upon in making an investment decision.

United Kingdom

This document is prepared and provided by Edison for information purposes only and should not be construed as an offer or sol icitation for investment in any securities mentioned or in the topic of this document. A marketing communication under FCA Rules, this document has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.

This Communication is being distributed in the United Kingdom and is directed only at (i) persons having professional experience in matters relating to investments, i.e. investment professionals within the meaning of Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, as amended (the "FPO") (ii) high net-worth companies, unincorporated associations or other bodies within the meaning of Article 49 of the FPO and (iii) persons to whom it is otherwise lawful to distribute it. The investment or investment activity to which this document relates is available only to such persons. It is not intended that this document be distributed or passed on, directly or indirectly, to any other class of persons and in any event and under no circumstances should persons of any other description rely on or act upon the contents of this document.

This Communication is being supplied to you solely for your information and may not be reproduced by, further distributed to or published in whole or in part by, any other person.

United States

Edison relies upon the "publishers' exclusion" from the definition of investment adviser under Section 202(a)(11) of the Investment Advisers Act of 1940 and corresponding state securities laws. This report is a bona fide publication of general and regular circulation offering impersonal investment-related advice, not tailored to a specific investment portfolio or the needs of current and/or prospective subscribers. As such, Edison does not offer or provide personal advice and the research provided is for informational purposes only. No mention of a particular security in this report constitutes a recommendation to buy, sell or hold that or any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.

London │ New York │ Frankfurt

20 Red Lion Street

London, WC1R 4PS

United Kingdom

More on Orell Fussli

View All

Latest from the Industrials sector

View All Industrials content

Research: Industrials

Metlen Energy & Metals — Strong 9M26 update

Metlen delivered a strong nine-month trading update (revenues only). Revenue of €6.2bn increased by 21% y-o-y (€5.1bn) and was a new record for the nine-month period, which saw growth and continued progress across the business. EBITDA guidance for both FY26 and the medium term was reaffirmed at €1.0–1.15bn and €1.92–2.08bn, respectively, and the company continues to work towards a potential METKA listing on Euronext Athens, subject to market and regulatory considerations. 2026 is continuing to shape up well, and we make no changes to our forecasts or our 50/50 DCF/SOTP €75.3/share valuation, which implies upside of more than 50%.

Continue Reading
Metlen Energy & Metals — Edison report on Metlen’s capital markets day
Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.