Sparks commentary - Avon Technologies

Industrials

Sparks - Avon Technologies

More on this equity
Avon Technologies (LSE: AVON) – strong FY26 delivery supports continued growth into FY27
Published by Harry Kilby

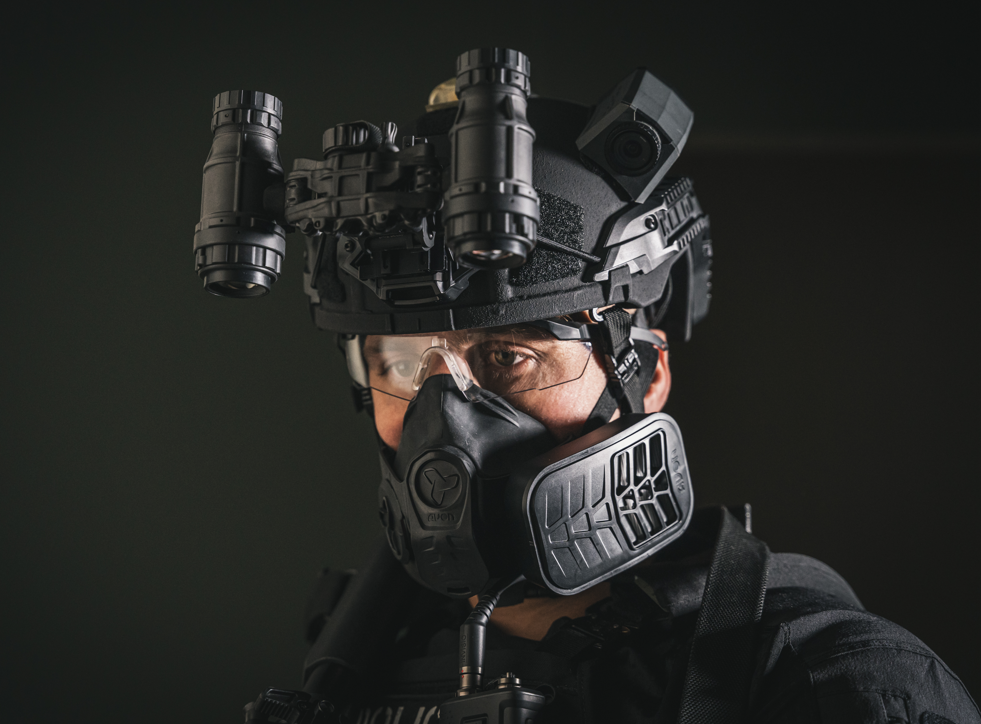
Avon Technologies reported FY26 revenue growth of 12.7% y-o-y to $353.7m, with adjusted EBITDA up 37.7% y-o-y to $70.9m and adjusted operating profit increasing 50.6% y-o-y to $60.7m. The adjusted operating margin improved by 440bp y-o-y to 17.2%, above the group’s previous 14–16% medium-term target, while adjusted PBT rose 58.7% y-o-y to $55.4m and adjusted basic EPS increased 57.1% y-o-y to 143.3c. Free cash flow increased 145.2% y-o-y to $30.9m, net debt excluding leases declined 32.7% y-o-y to $33.7m and leverage reduced to 0.43x from 0.86x. ROIC increased by 900bp y-o-y to 27.6% and the total dividend rose 8.9% y-o-y to 26.8c/share. Avon Protection revenue increased 12.7% y-o-y to $190.3m, while Team Wendy revenue rose 12.6% y-o-y to $163.4m, with margin expansion across both businesses supported by higher volumes, operational improvements and IT savings, alongside favourable mix in Avon Protection and some one-off benefits including US tariff refunds and tax incentives. The group completed its STAR transformation programme during FY26, exceeding its 2027 revenue, margin, ROIC, cash conversion and leverage targets a year early, while the closing order book remained broadly unchanged at $262.7m, providing good visibility into FY27 and beyond.

For FY27, management expects mid-single-digit revenue growth, an adjusted operating margin within the 16–18% target range and free cash flow of approximately $50–60m. These expectations are consistent with medium-term targets of more than 5% annual revenue growth, adjusted EPS growth above 10% per annum and more than $175m of cumulative free cash flow over the next three years. Longer term, Avon sees a pathway to more than $600m of revenue within five years under its Improve. Grow. Compound. strategy, supported by further operational improvement, international expansion, new US and NATO protection programmes and selective acquisitions in adjacent protection technology markets. Management highlighted the US CBRN suits programme, where Avon has reached phase three and secured an initial 1,500-system order for FY27 trials, alongside further respiratory and head-protection opportunities. Near-term risks include sustaining Team Wendy’s higher production levels, potential delays to US contract awards and lot acceptance, and uncertainty around the timing and probability of new programme wins.

While the FY26 performance was strong, FY27 margin guidance of 16–18% implies broadly stable progression from the 17.2% achieved in FY26, while order intake increased only 0.6% y-o-y and the closing order book was broadly unchanged.


Cookie Policy Overview
Edison Group

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping us understand which section of the website you find more interesting and useful. See our Cookie Policy for more information.

Strictly necessary and functional

These cookies are used to deliver our website and content. Strictly necessary cookies relate to our hosting environment, and functional cookies are used to facilitate social logins, social sharing and rich-media content embeds.

Advertising

Advertising Cookies collect information about your browsing habits such as the pages you visit and links you follow. These audience insights are used to make our website more relevant.

Performance

Performance Cookies collect anonymous information designed to help us improve the site and respond to the needs of our audiences. We use this information to make our site faster, more relevant and improve the navigation for all users.